Insight from the trenches.
30 April 2014
Covered on the blog a while back, Tesco have implemented 'defensive' fresh merchandising tactics for low sales density stores.
Whilst this is a great initiative from a Tesco viewpoint, reducing shelf space, making shelves look fuller without dropping the range or turning chilled units off, it does raise questions about these stores in the North.
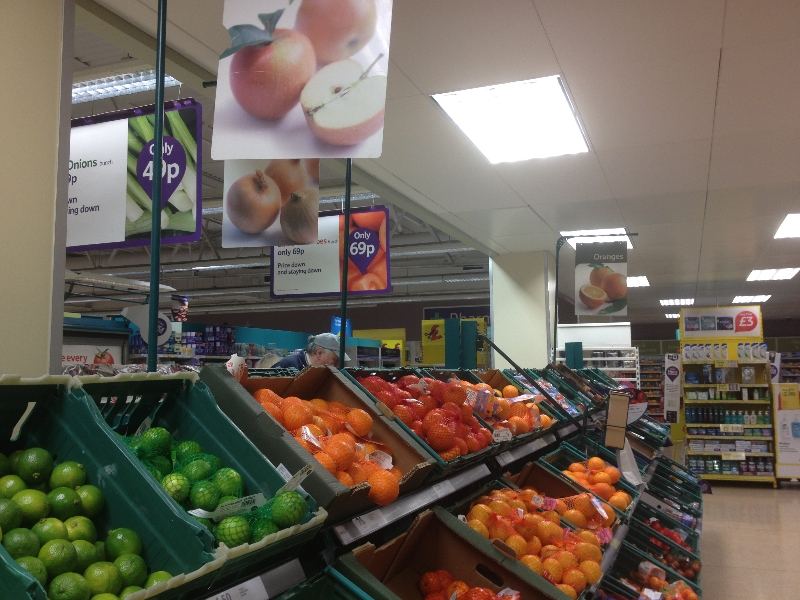
Top tier shelving is removed from the Produce category, with no discernible impact to customers. The defensive fresh merchandising will save cost for Tesco around waste, with stock driven in to fill shelves.
However, this store is relatively small and even the Extra in Bradford itself has adopted this tactic, space can't be blamed in this example; so how do Tesco grow sales in a smaller shop?
Why are Tesco lagging in the north?
Aldi are notably strong in the north, Asda in their territory are fighting back and Morrisons, despite suffering from negative sales for two years now are still strong in the north.
Tesco have their issues across the country, but particularly within the north. Is it time for some new thinking?
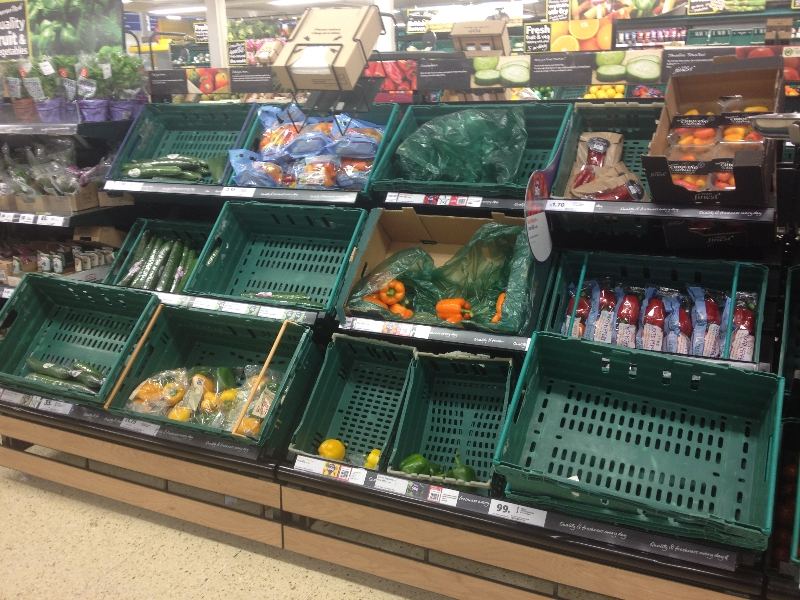
Standards from Tesco remain a challenge, going into late night on a busy Saturday saw standards such as this. There are some allowances for the trade level, but how long does it take to make things look presentable?
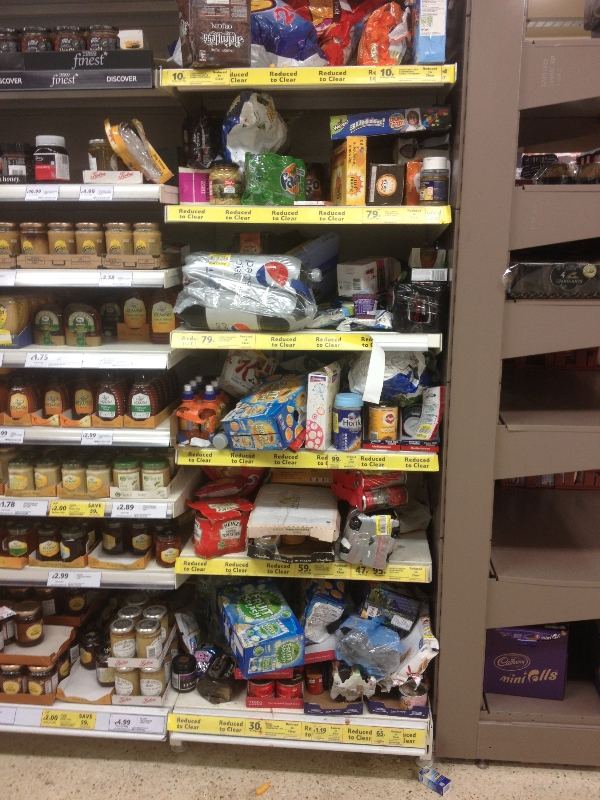
A disaster of a reduced to clear area will see nothing sold from this display, even if it was all 20p. Inexcusable. I understand shrinkage is an issue, and money in the till is important but the majority of this stuff needs to be disposed.
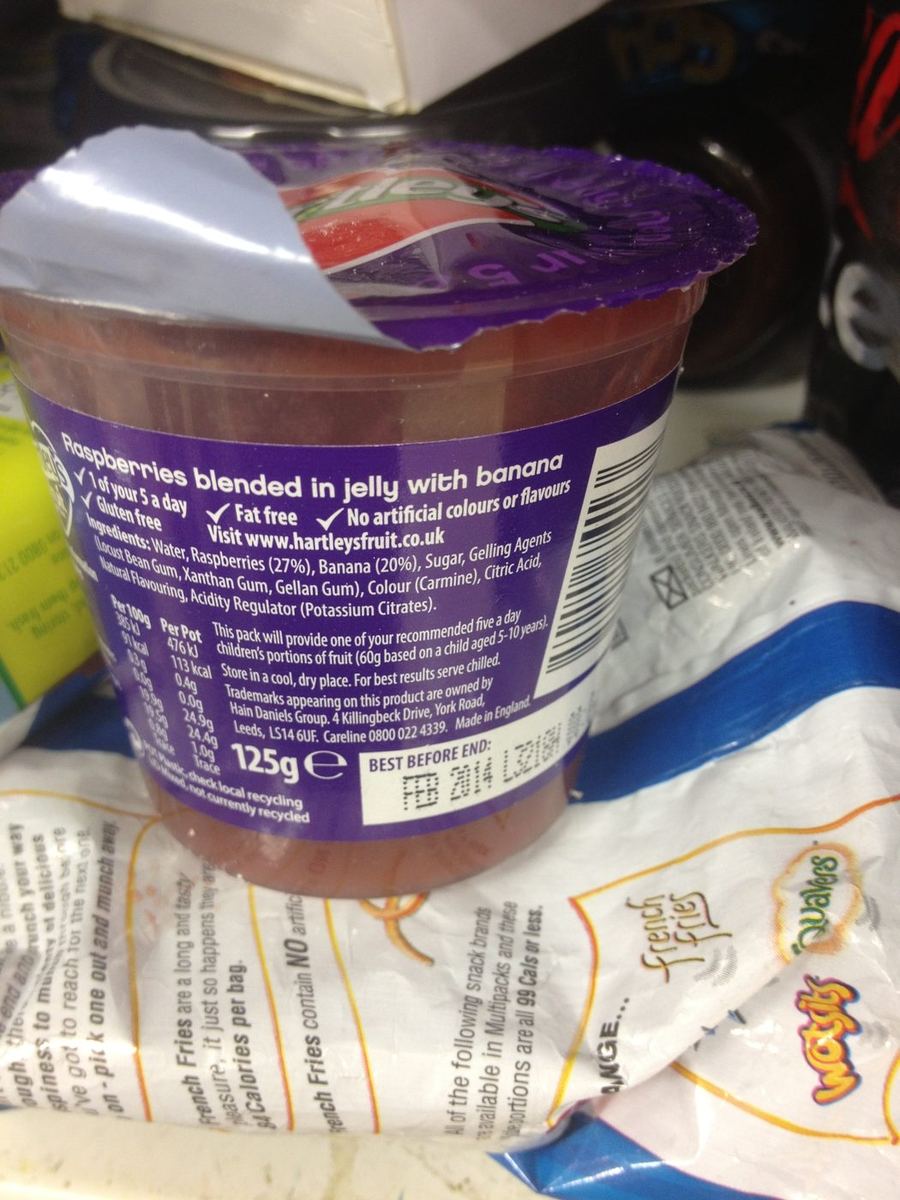
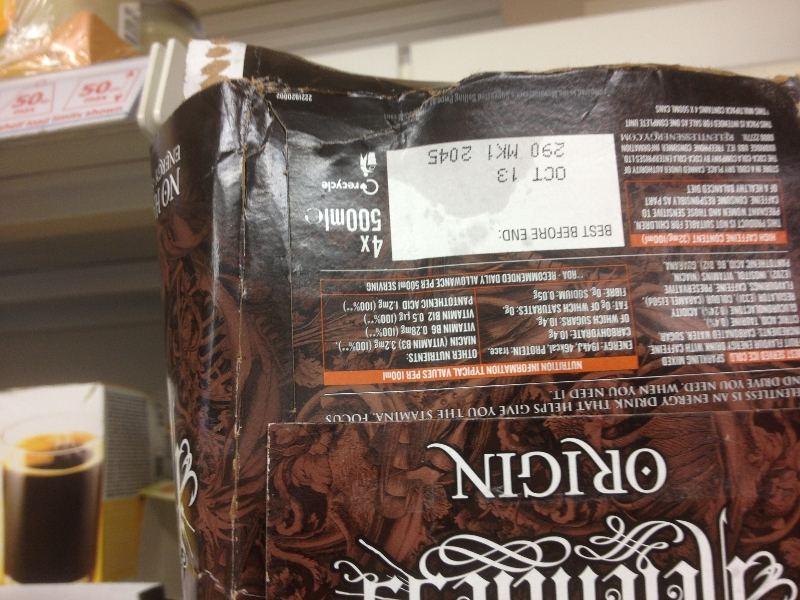
Out of date food on the shop floor sends out a worrying message, this area is located near fresh food counters, which then raises further questions to customers. Lest they start thinking about what must lurk behind the fresh counters.
The concern is how many people have walked past this? How many visits since October has the store had? Over Christmas? Presumably more stock has been added to the display?
I just can't understand how it has been allowed to get so bad. In a decent refitted Extra too.
Sainsbury's continue to turn the wheel and it'll be tough for them now growth has disappeared from the market. They trade on provenance and values which are important, but customers do pay a price for this on own label.
The issue for Sainsbury's is their pricing, they have a significant gap on own label versus their main competitors, let alone Aldi, who also are trading well under a good provenance banner - 100% British meat for example.
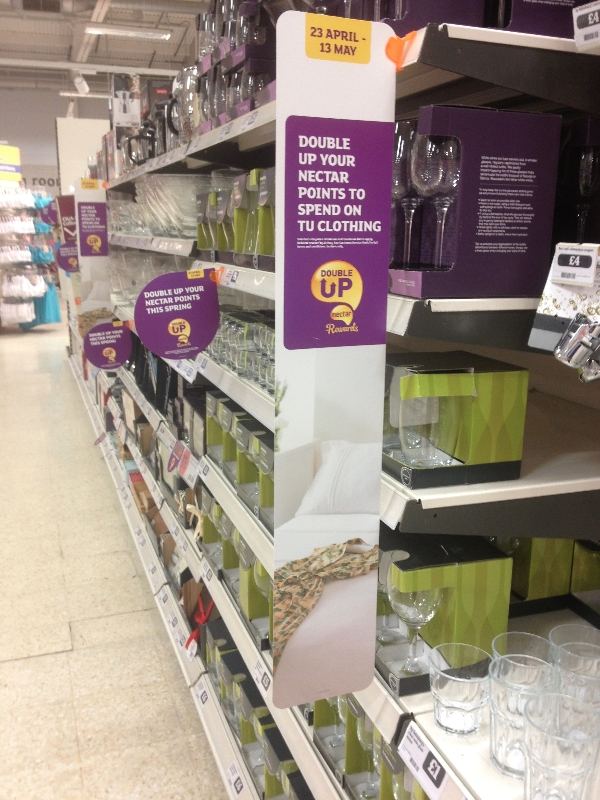
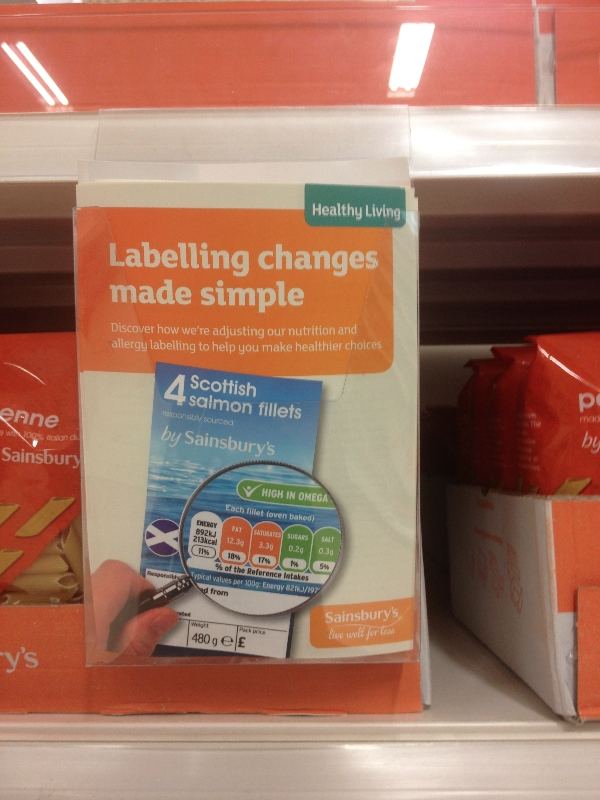
The latest health wheel changes are also coming in at Sainsbury's, with PoS advertising the changes. In addition, as is typical over these bank holiday weekends; JS are trading a double Nectar points event on selected GM categories.
This is restricted to their XL format stores - those are the largest within the estate.
Aldi continue to trade very well, and expanding their range is always a consideration to enhance the appeal. The problem is that their model is centred around 1300 SKU's (up to 1500) and within this, it's difficult to cater for every single niche.
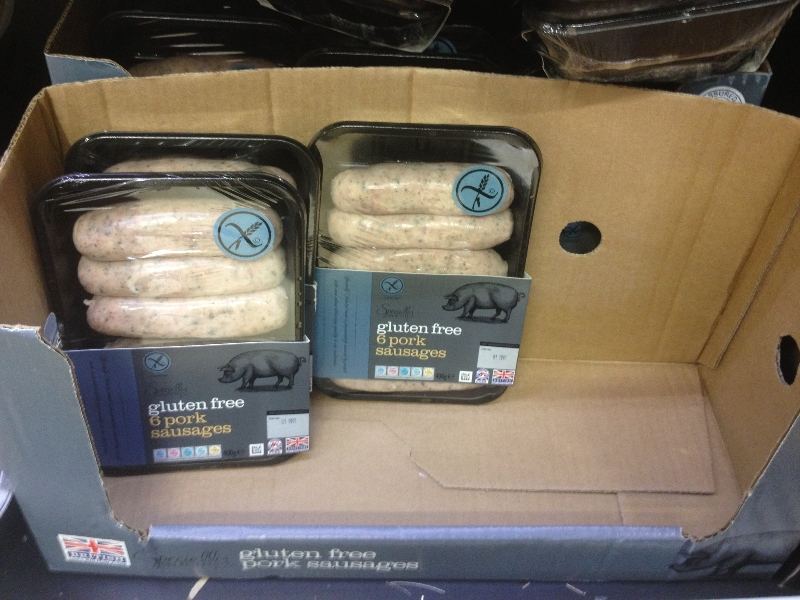
Gluten Free Sausages have been dropped in as part of a 'special' promotion within their Super 6 for Meat / Fish. These are proving popular and may see further lines ranged for customers with intolerances.
Dietary food such as this is a conundrum for retailers as it's relied upon by a small (but growing) number of customers but is typically highly priced due to the specifics of producing.
This means that wastage in a (£) sense is higher, and sales cannot be boosted by promotions given the special aspect of the range and those that purchase it.
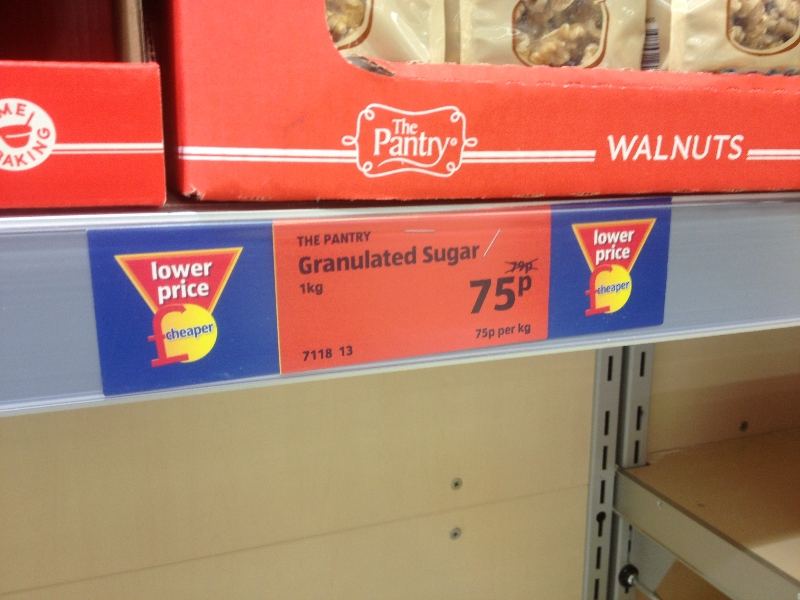
As discussed a recent email, we knew Tesco were price matching Sugar at the Aldi level (79p). As we see from Aldi, they simply drop their price by 4p to be the cheapest in the market.
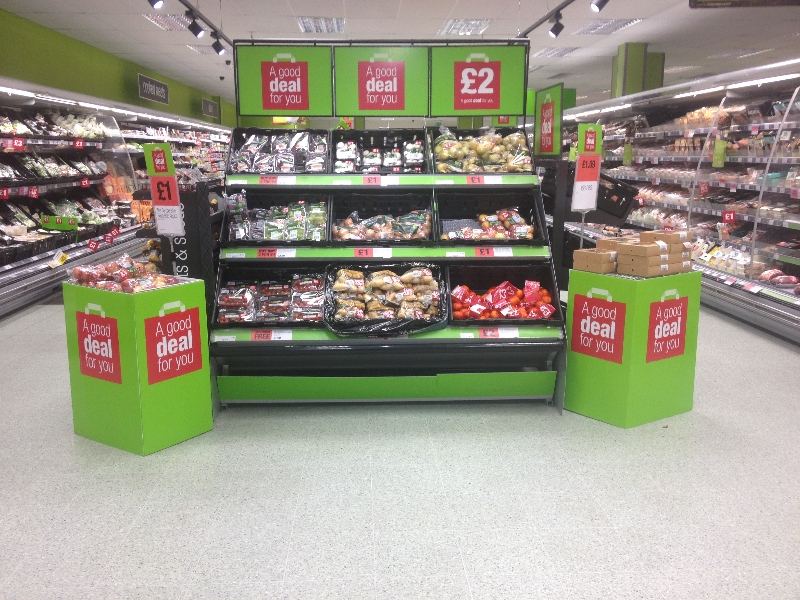
As we know, a major price initiative from the Co-Operative sees their pricing come more into line with key competitors (Tesco Express & Sainsbury's Local).
The next email will focus on how much this campaign has closed the gap with their key competitors.
Value / A good deal for you continues to be a focus for the Co-Operative, a strong PoS package on this gondola end certainly caught the eye.
Lower prices are appreciated by the customer, but promotions within the Co-Operative remain important to those 'top up' shoppers.
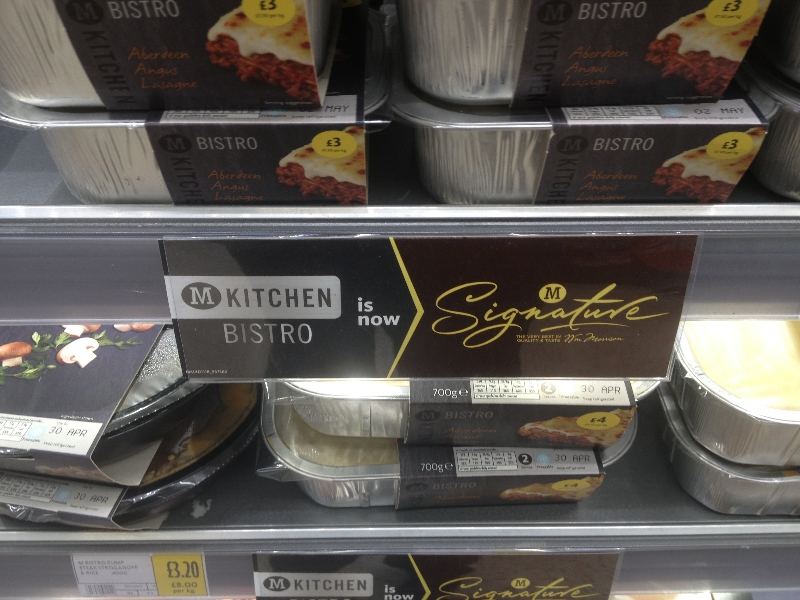
Little going on within Morrisons, bar the former directors criticising the incumbents which should make for an interesting AGM in June.
The collection of sub brands intended via Richard Hodgson never materialised and as such, Bistro is now being backed out of with this being incorporated into the enlarged Signature premium tier.
Grocery Insight offer a range of services to retailers, suppliers and investors. Looking at categories across retail to shape an upcoming range review, looking at your stores undercover to highlight areas for improvement or to provide some 'expert' insight into a project or proposal.
We can always help, our 'feet on the ground' approach means no one knows the retail market like we do.
From the Grocery Insight newsletter archive, first sent to subscribers on 30 April 2014. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.