Food 'to go' for Tesco London
7 April 2014
Food service at Tesco
A new Tesco obsession.
The advent of in store food offering was dismissed by Tesco under Sir Terry, with several of the in store cafes sub contracted to Eurest (and indeed Elior) and other such faceless companies.
The mere idea that an in store eating experience could positively / negatively affect how a customer viewed the packaged food being sold in store was beyond Tesco. An example of saving over serving, it went too far.
Lest we forget, the majority of the Tesco cafes remain under 3rd party ownership which may look good on the balance sheet, but when you're enhancing your fresh food offer, it doesn't make a great deal of sense outsourcing the food operation in store.
Consider that Sainsbury's are very good at progressing their in store cafe offer, with links to 'taste the difference' on the menu. Similarly Morrisons with their new menu links back to Market Street and the food on offer in store.
Tesco realising their weaker in store offer got ahead of the curve when they bought into Harris & Hoole coffee, Euphorium bakery and now appear to have invested a stake in 'Freds' which is a new concept cafe in Osterley Extra, London.
Of course, the biggest acquisition was that of Giraffe over a year ago now, and save for an implant into Watford and a few Giraffe 'bars' in store. There's been little else developed with that brand, Decks was dropped into Coventry as a standalone restaurant and it remains to be seen whether that goes beyond one store.
There have been some further standalone developments, 'Yoo Moo' Ice cream have a unit in an Extra store in Brent Cross for example.
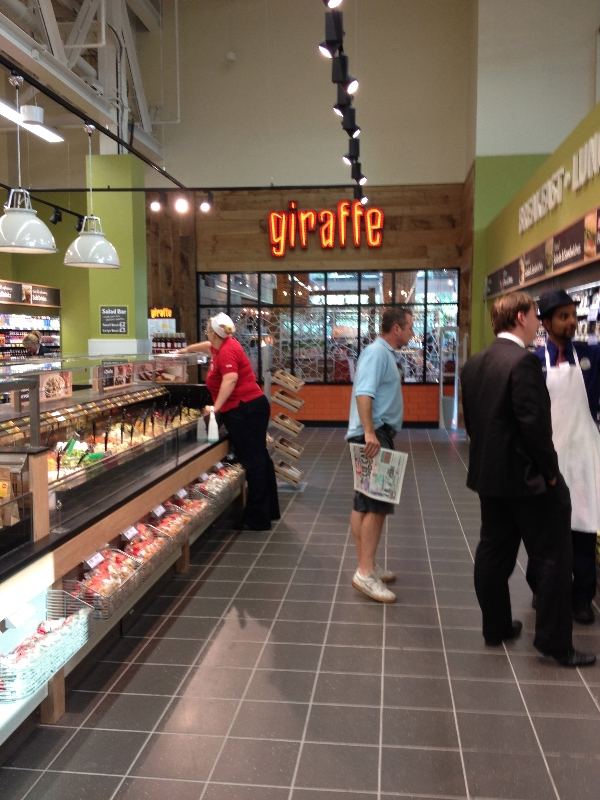
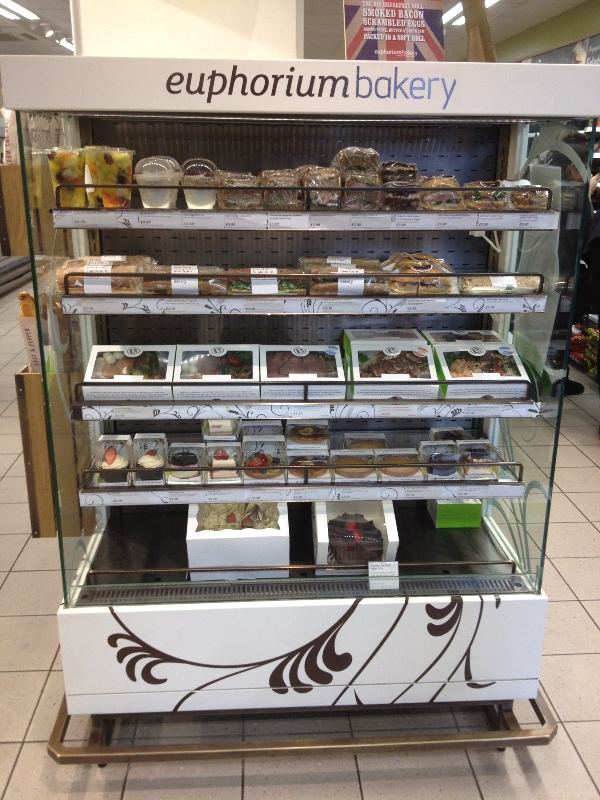
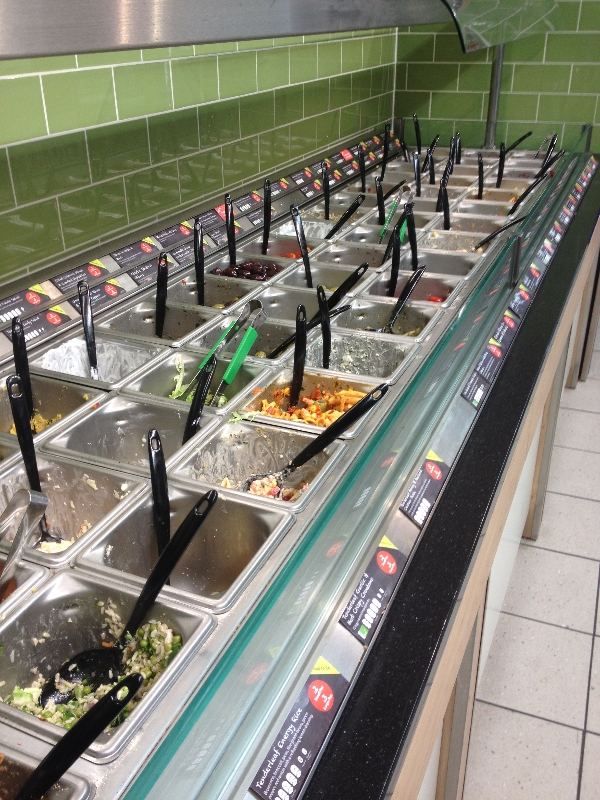
Euphorium offer an artisan range of breads in some Tesco stores in the capital, there is a real focus on 'Food to go' in London Metro / Express stores with an expanded sandwich offer, salad bars and a 'to go' offer in stores that can support it.
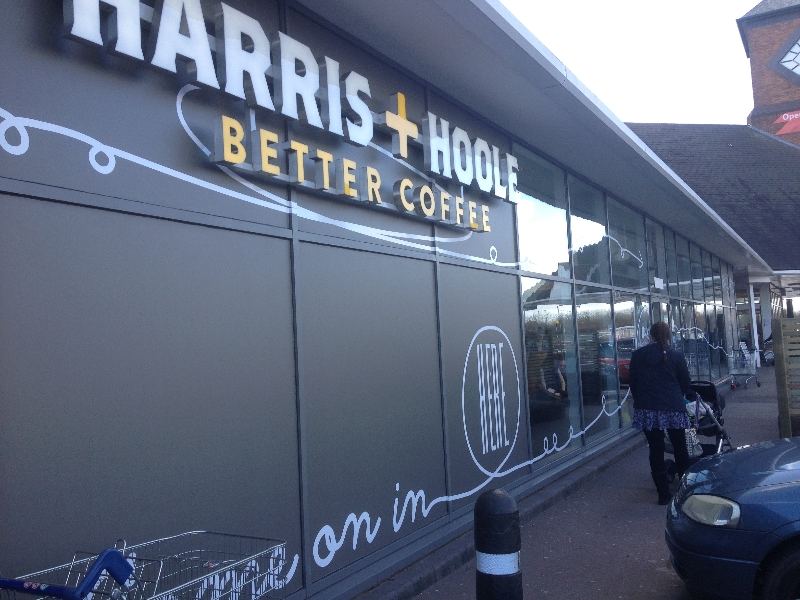
Harris & Hoole has also started to pop up in stores local to the capital such as Tooley St. Further afield, the Hatfield store has a Harris & Hoole implant and the development of this offer makes sense.
Tesco stores have a number of Costa coffee concessions and converting these to a business that is part owned by Tesco makes sense.
There are logistical challenges though, the infrastructure for Harris & Hoole and indeed Euphorium are based within the M25. This makes supplying stores further north a real challenge, which can make the Extra remodel (a la Watford) a harder task to achieve.
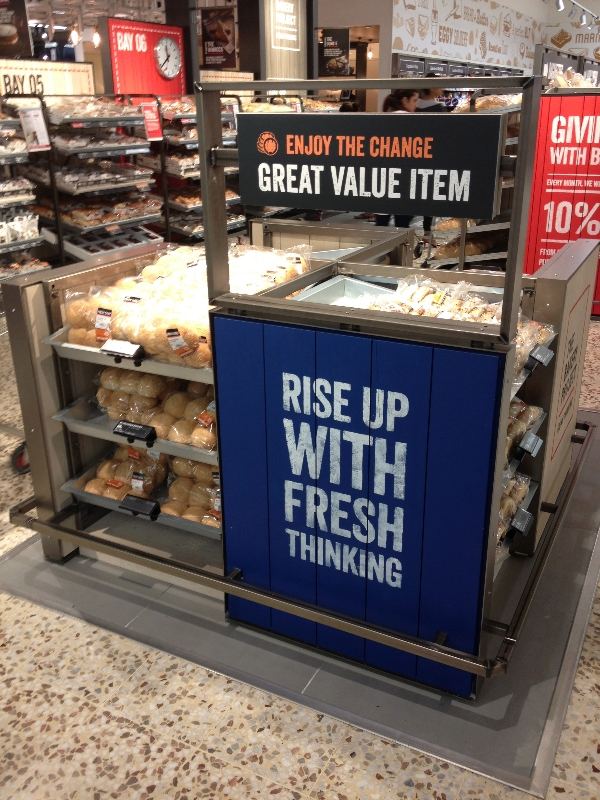
The Bakery project eliminates baking in store, allowing products to come in via the central bakery at Euphorium, allowing a deeper, more varied range and a more consistent level of standard within the category.
So, with Tesco facing a real over spacing issue, it seems to make sense that they discuss branching out into food service as a way to both generate revenue, footfall and solve some of their over spacing problems.
But what of the rest of the country? There seems to be painfully little going on beyond London and the leafy Hertfordshire borders. There are stores within Bradford for example that need new thinking beyond what is being trialled now.
Euphorium and Harris and Hoole make sense within the capital as it allows better margins on Coffee, Bread and Sandwiches whilst also enabling a real point of difference with the offer, but what of the rest?
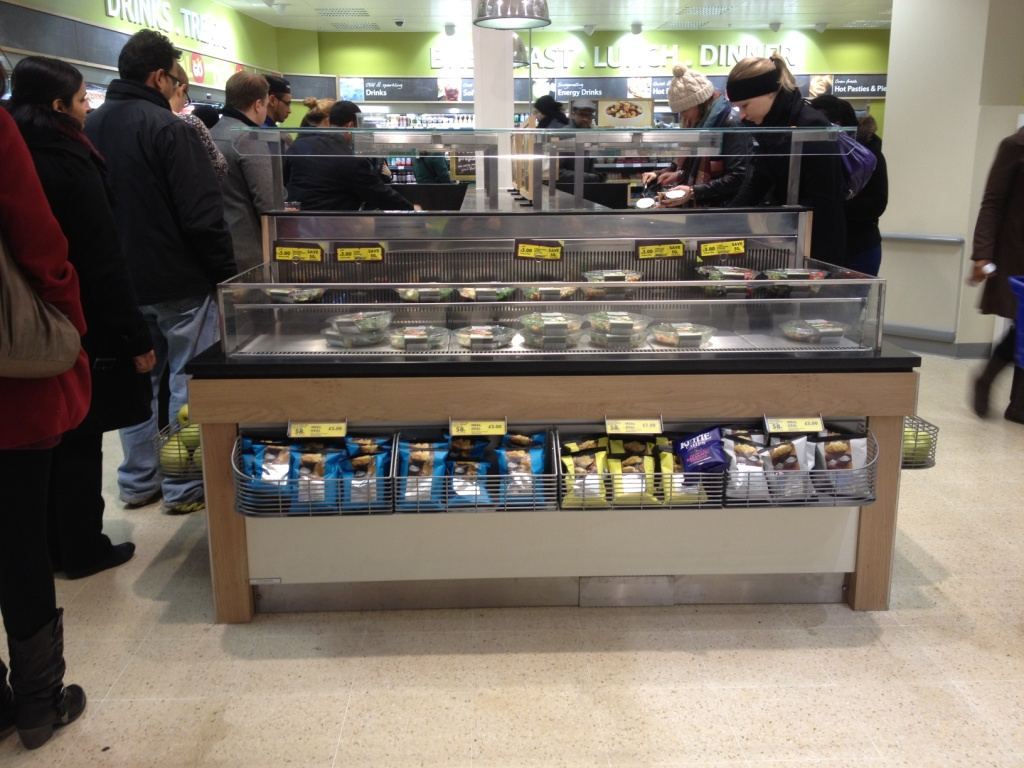
Looking beyond this, and buoyed by their success in London with Food to go, Tesco are going to roll out around 80 stores within London initially that will focus on a 'food to go' offer.
These stores will be smaller than an average Express but offer 'food to go', with Coffee, a Salad Bar, Bakery and 'food for later' offered.
A reduced store size (c 1k sq ft) allows them to get into more locations that are otherwise impossible within the Express framework, taking them head on versus the Pret / Eat of this world.
Tesco may have struggles, but there is little doubt that London, under the stewardship of Andrew Yaxley is going from strength to strength.
This email service is going subscription only.
I know you're overwhelmed with generic, rewritten press releases and non specific insight from the food retail space.
This email service will fill in those gaps, offering incisive trend spotting, covering new stores and day to day 'from the ground' store insight rolled up into thrice weekly emails.
Subscription is £20 per month (66p a day!) and for a limited time, there's an extra month free for subscribing today. I'll also send out a detailed store report of the Co-Operative 'Gen2' store format too.
Can you afford to be without it?
Twitter Website LinkedIn Email
Grocery Insight provides market insight on the food retail market, whether its an 'instant update', monthly overview or fuller in depth research into individual retailers.
Insight can also be provided for retailers, with analysis on operations, store performance and the market. Whether it's their own stores or the competitors.
An expanding area of the business is the investor services, keeping investment management companies abreast of the latest developments in the industry, at a time to suit you.
For a no obligation chat, please email: [email protected]
From the Grocery Insight newsletter archive, first sent to subscribers on 7 April 2014. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.