Retail by email - No. 4468 - Tesco pushing margin
1 March 2022
Let us help you with customised market insight and perspectives.
View this email in your browser
Retail by Email - Issue 468 - TescoTesco pushing Finest and marginThe Tesco price matching scheme versus Aldi has its origins in Ireland. Back in 2015 (and before) the business was hammered quarter after quarter with the wrong strategy and facing in to the same cuts to labour and stores that had seen the UK business bleed market share too.
The Irish market is fierce and not only are Tesco and the discounters present, there are also natives in Supervalu (majority independently owned) and Dunnes (family owned, M&S esque) alongside a legion of strong independent convenience stores too.
Tesco Ireland; pre Dave Lewis were struggling, their stores weren’t good enough and they were being dragged in to the voucher game trying to prop up poor sales. Both Supervalu and Dunnes alongside the discounters were often offering money back when a customer spent a certain amount (€5 off €40 e.g.) Dunnes ran a near permanent voucher scheme with tiered vouchers for each spend threshold - €5 off €50 / €20 off €125 etc) to great effect.
With vouchers in the mix, it becomes a race to the bottom and Tesco Ireland just weren’t doing enough. Andrew Yaxley and co then embarked upon an EDLP low price focus whereby they matched Aldi on almost every product (mid tier, not just value) which led to a flattening of the price differential and Tesco becoming a great value place to shop.
Whilst price matching was important; Tesco had a number of elements in their own control too; such as store standards being a key one. A better Produce department is another and uplifting core own label ranges with better provenance messaging (crucial for the Irish market).
The UK, boosted by success with their own price matching scheme versus Aldi (more of a focus on value tier lines in the UK campaign, with some mid tier lines appearing in recent months) have now started to uplift Finest, both to boost margin with their Aldi price work but also, possibly, to capitalise on customers making choices around switching a meal out for a ‘meal in’ given the rising cost of fuel and indeed, food too.
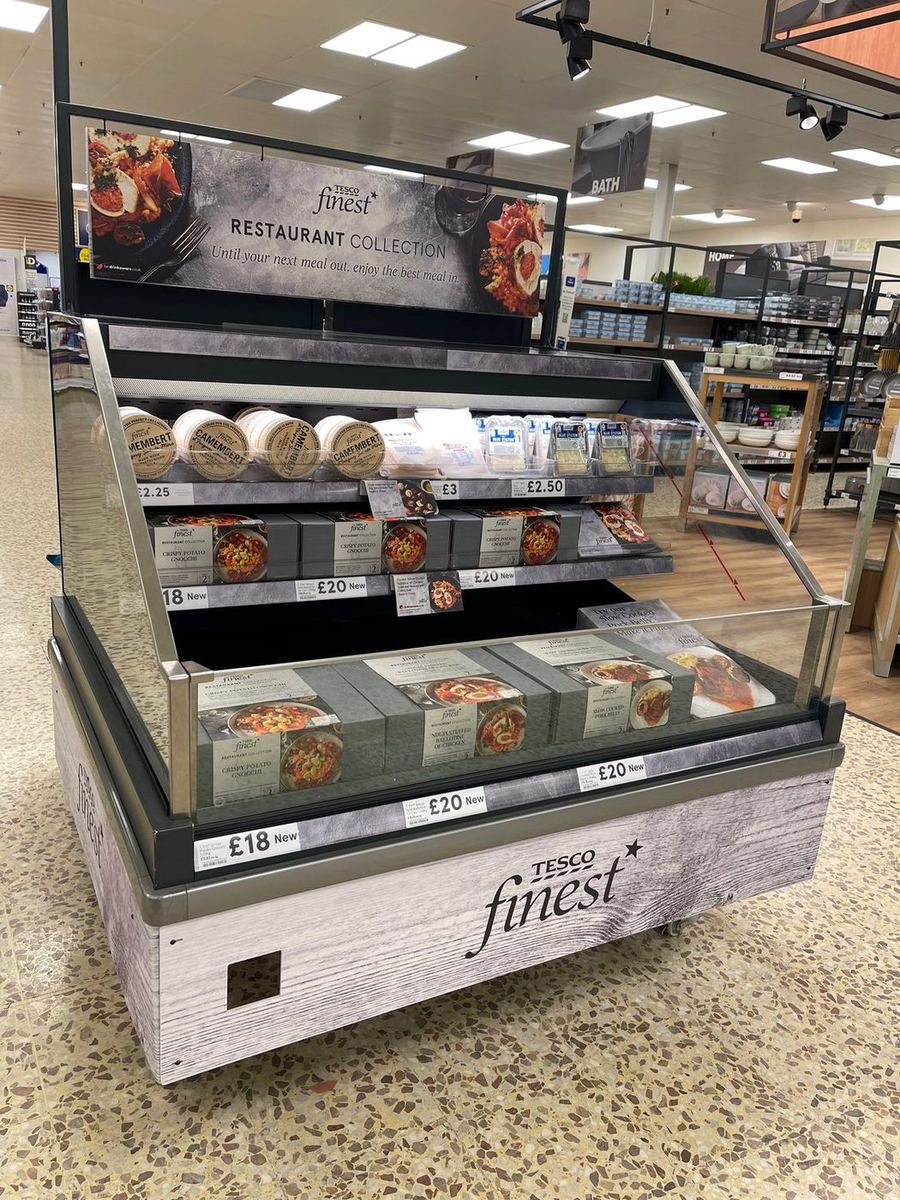
With customers feeling reassured; the focus in Ireland went to driving margin with improvements at the premium tier end of things. Enticing customers to spend a little more on a treat or two perhaps.
The price war was fierce in Ireland; the lowest price that Cream Crackers got to was an unbelievable 12c.
The commitment by Tesco UK to “follow Aldi up, or down” on price was notable and this mentality has transferred across to the UK business, given the recent price rises in Aldi then followed by Tesco.
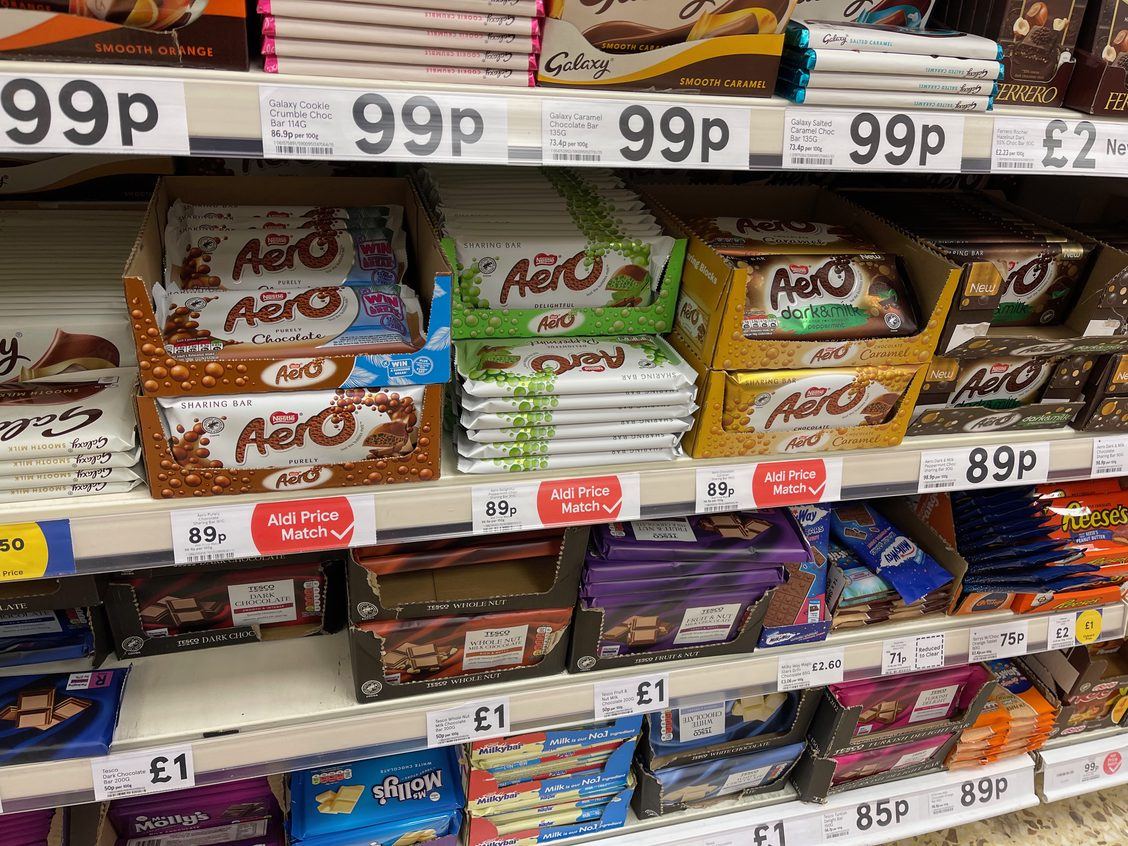
With price matching highlighted at the shelf edge in the UK business remaining strong and brands also highlighted here. This message has been solid since 2020 (just pre pandemic) with more brands and own label products compared against Aldi than ever before.
It all kicked off with farm brands of course, followed then by a wholesale revamp of the entry level tier products and then the price matching versus Aldi with more products and tiers added, as appropriate.
Thus; with customers feeling the benefit of the Aldi price match and lower prices in their shopping basket; it’s time for Tesco to drive the premium own label and indeed add sales via some value “pillars” like the “dine in” meal deal too.
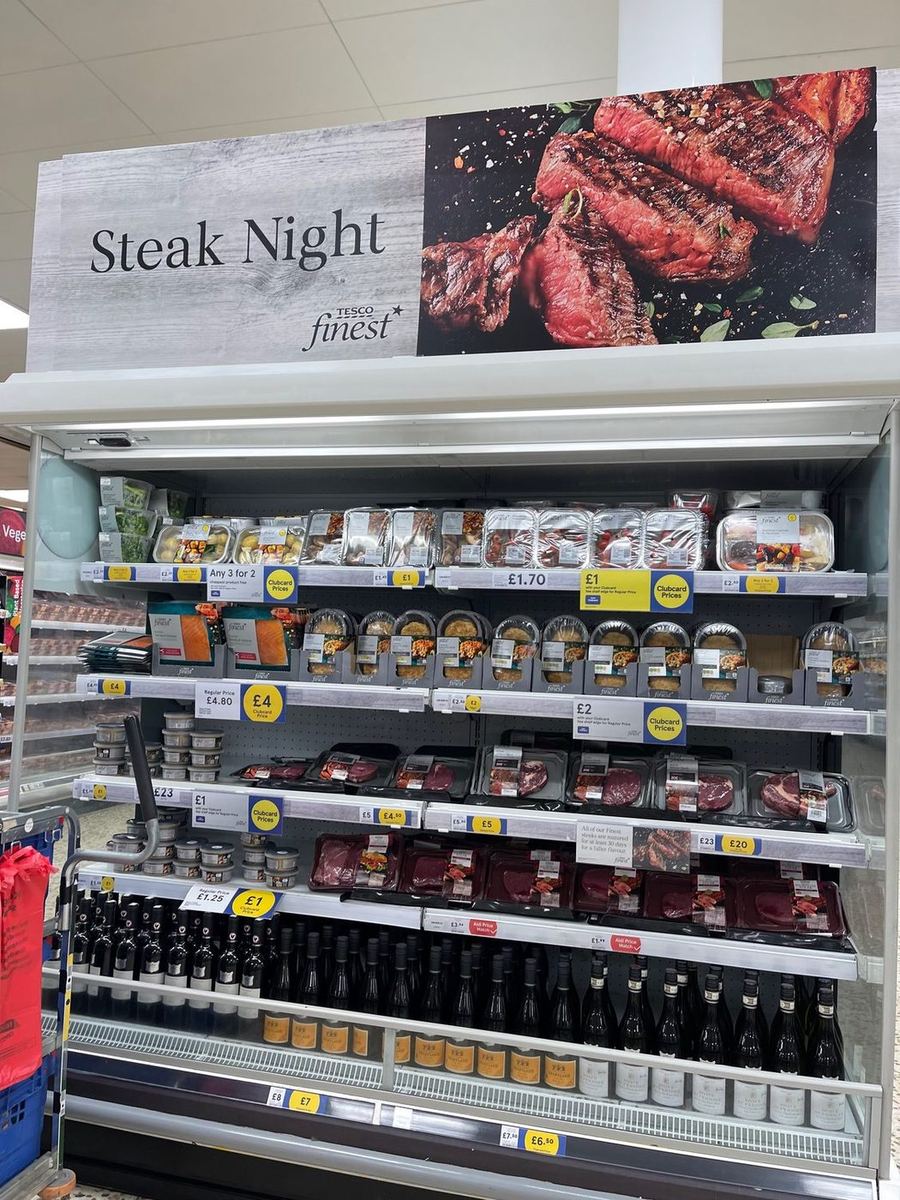
Finest Steak Night has been a focal point on the end in Tesco for a while now; driving the appeal for customers “treating” themselves with the premium tier.
Offering Wines too in the same end notably.
Of course this could be a ‘consumer spending squeeze” tactic too; with customers looking to save money and potentially sacrificing a meal out in favour of a Finest meal deal (or similar).
Which was something Tesco did to great effect back in 2008 in the great recession; under Sir Terry Leahy of course. Focusing on premium to look after customers who were wanting to save in some areas and were happy to spend extra on trading up (for example).
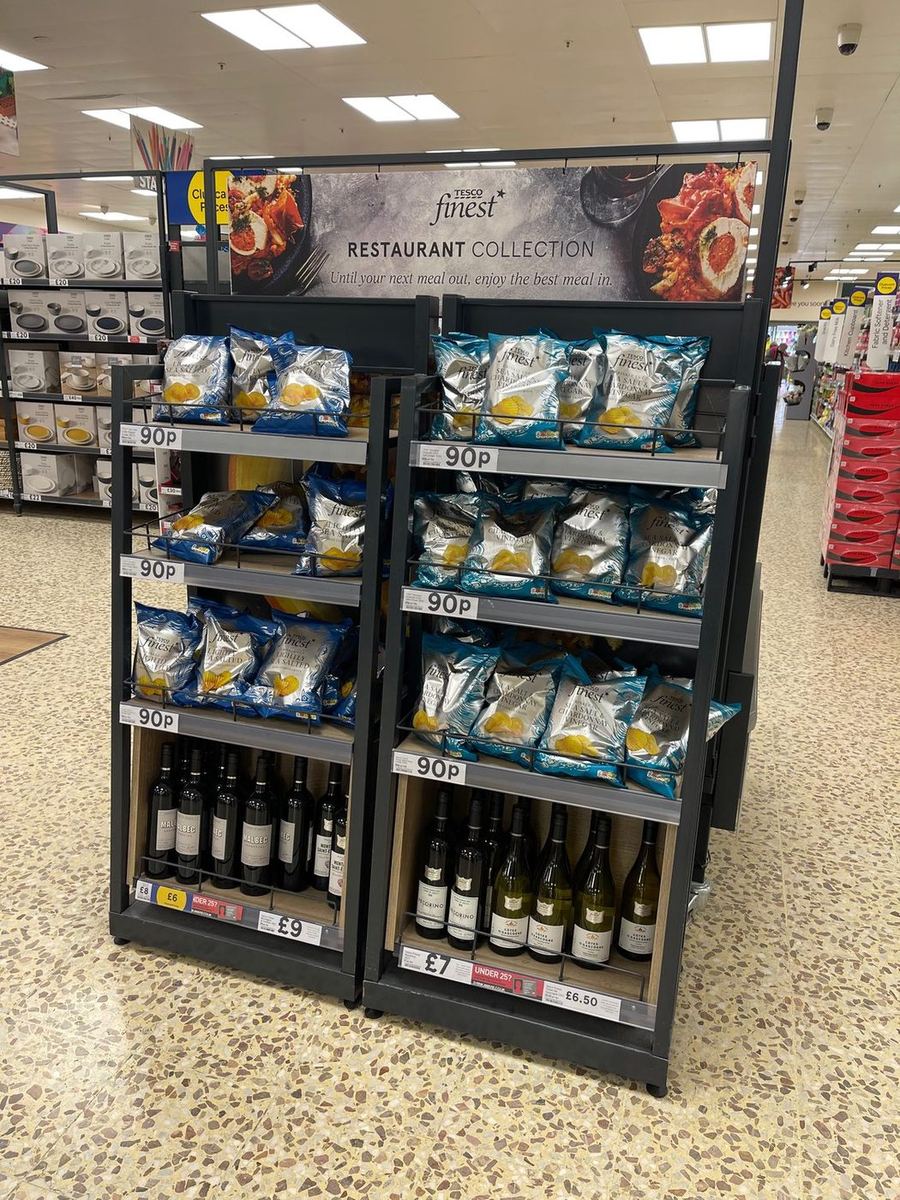
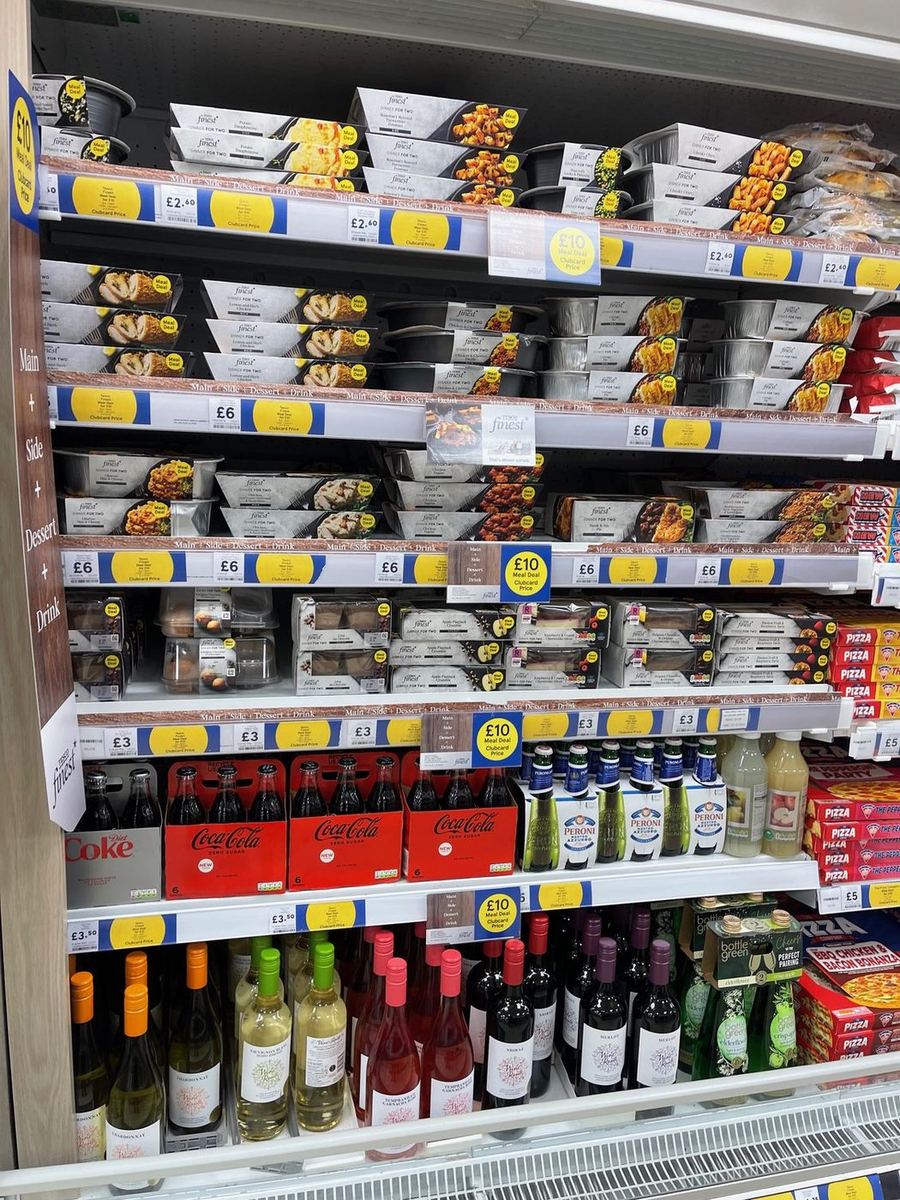
The ready meals were assorted with separate deals within the core category.
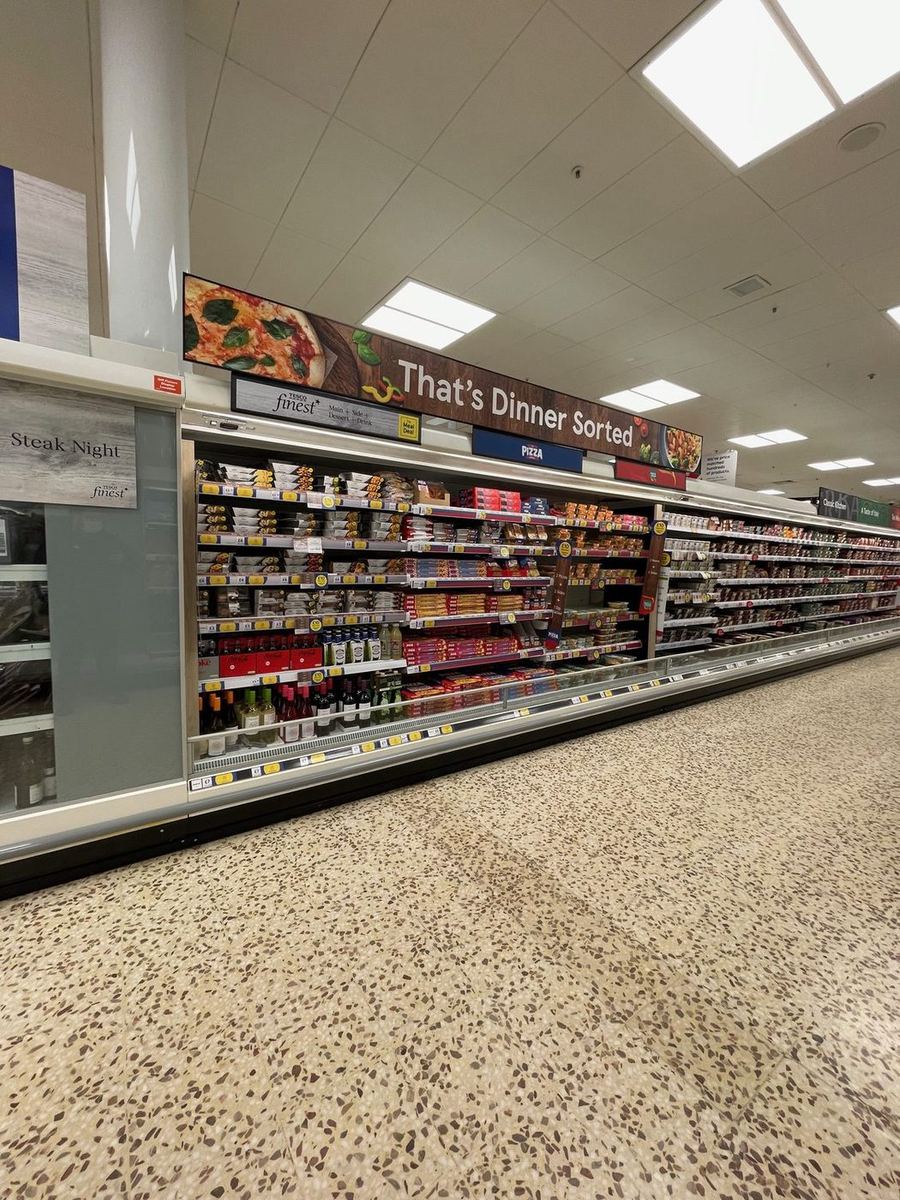
Signage highlighting “That’s Dinner Sorted” signposts these offers to customers, Tesco have also utilised Jamie Oliver to good effect in this space too with various meal inspirations.
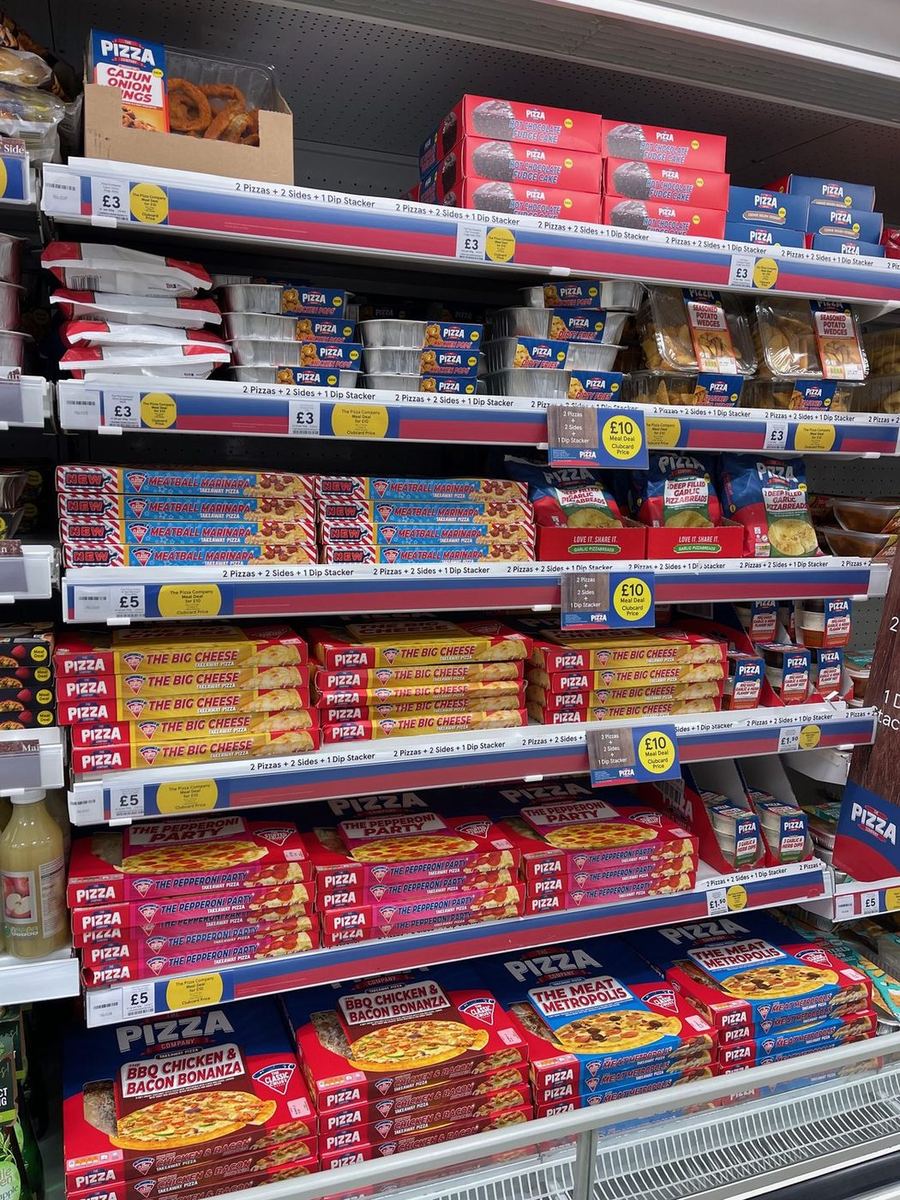
It’s not just Finest that benefits either. Tesco has a “Domino’s” style Pizza Meal Deal and this is another staple in the Chilled aisle.
Offering more options for customers, again, wishing to trade down from Domino’s to save money or indeed treat themselves due to savings made elsewhere.
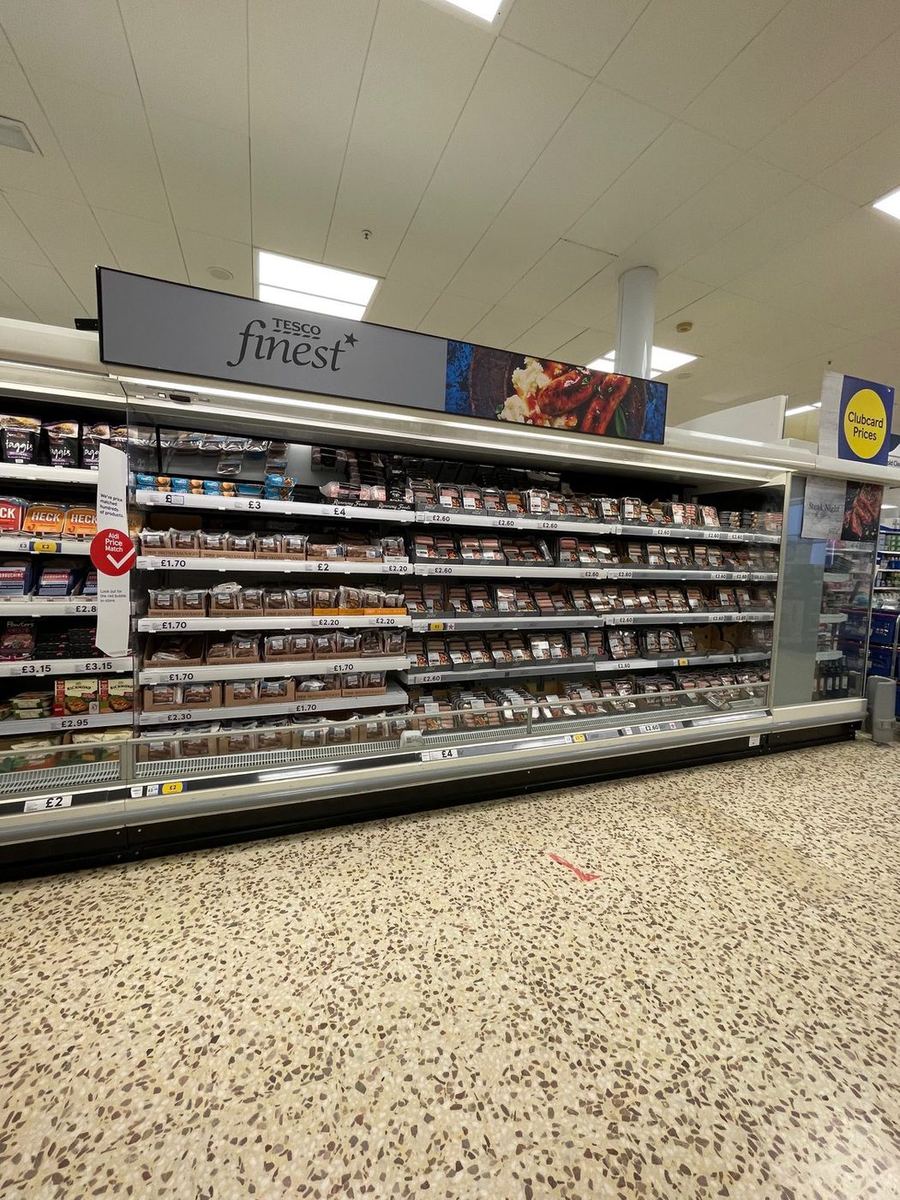
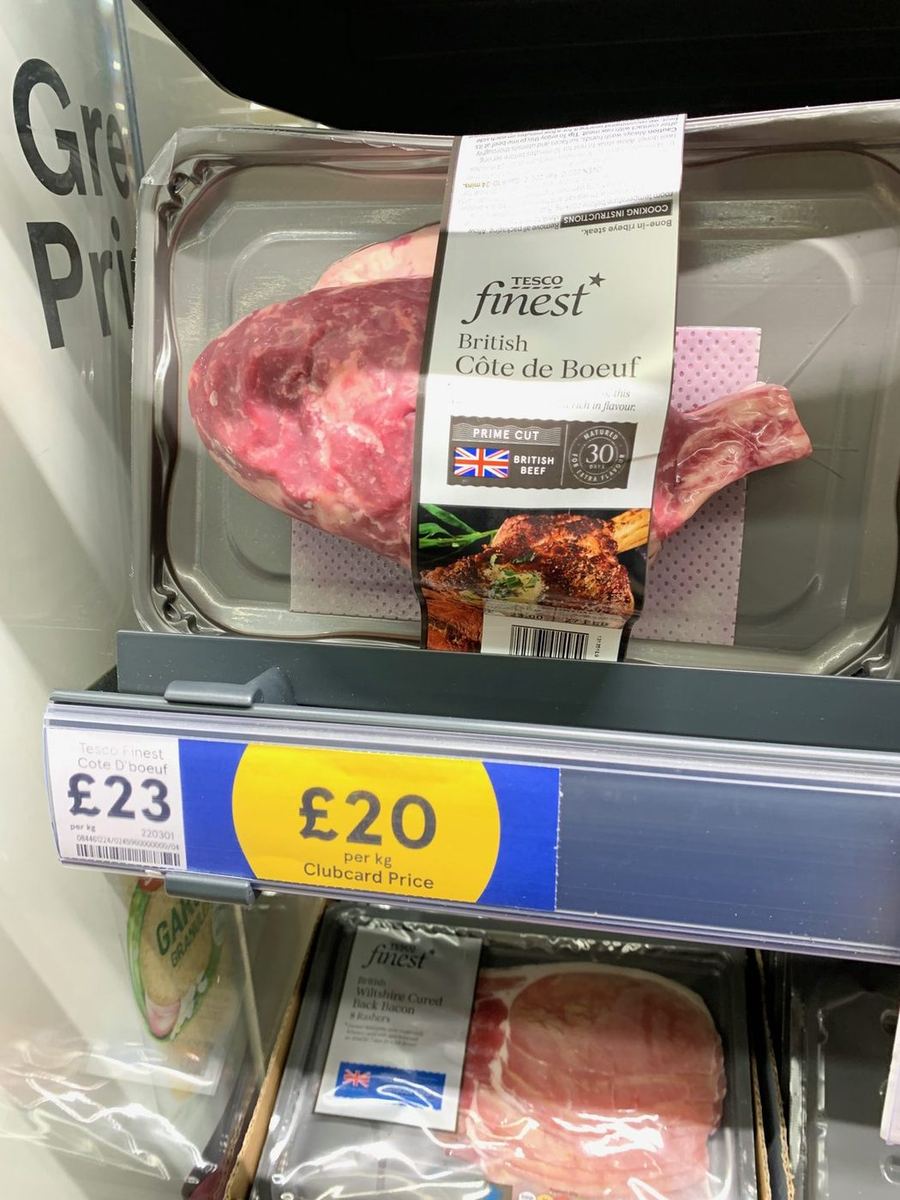
The wider Finest range is also given a halo within aisle too (Meat here); an attempt to drive margin given the relative success of the price matching scheme versus Aldi, but also provide customers with more choice than purely “price matched to Aldi” product.
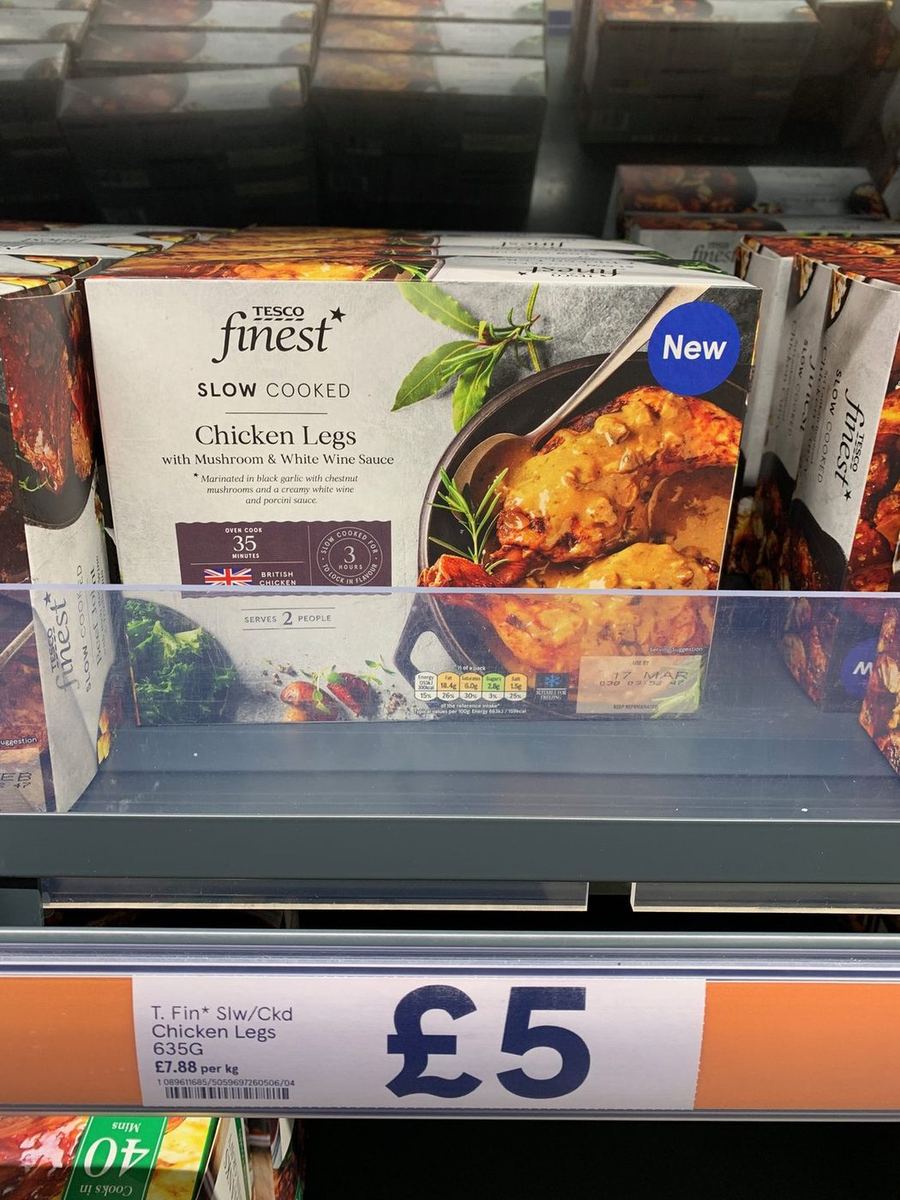
Indeed; so successful was the Tesco v Aldi price matching; Sainsbury’s then aped the scheme and the rebadging of the value tier lines too. Before realising it was quite expensive to price match quite so many lines (indeed, they matched far fewer in any case, I think c. 240 at launch).
Now it’s 150 items versus Aldi.
The challenge with inflationary territory that we are in is that any form of price lock (which is what the Aldi vs. JS scheme is) means that prices rise once the product comes off any form of “lock” or “match” or the products change.
It has the reverse effect of then amplifying any price rise…..
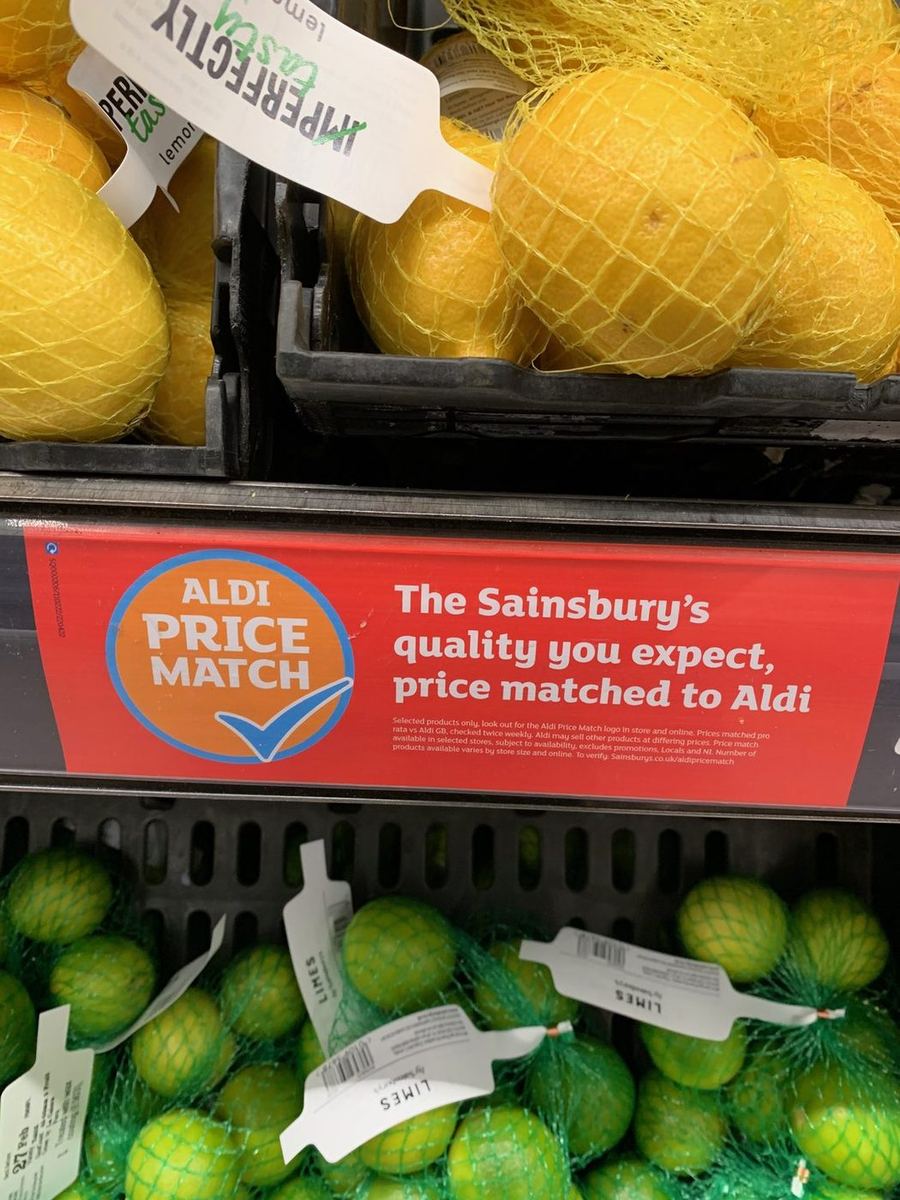
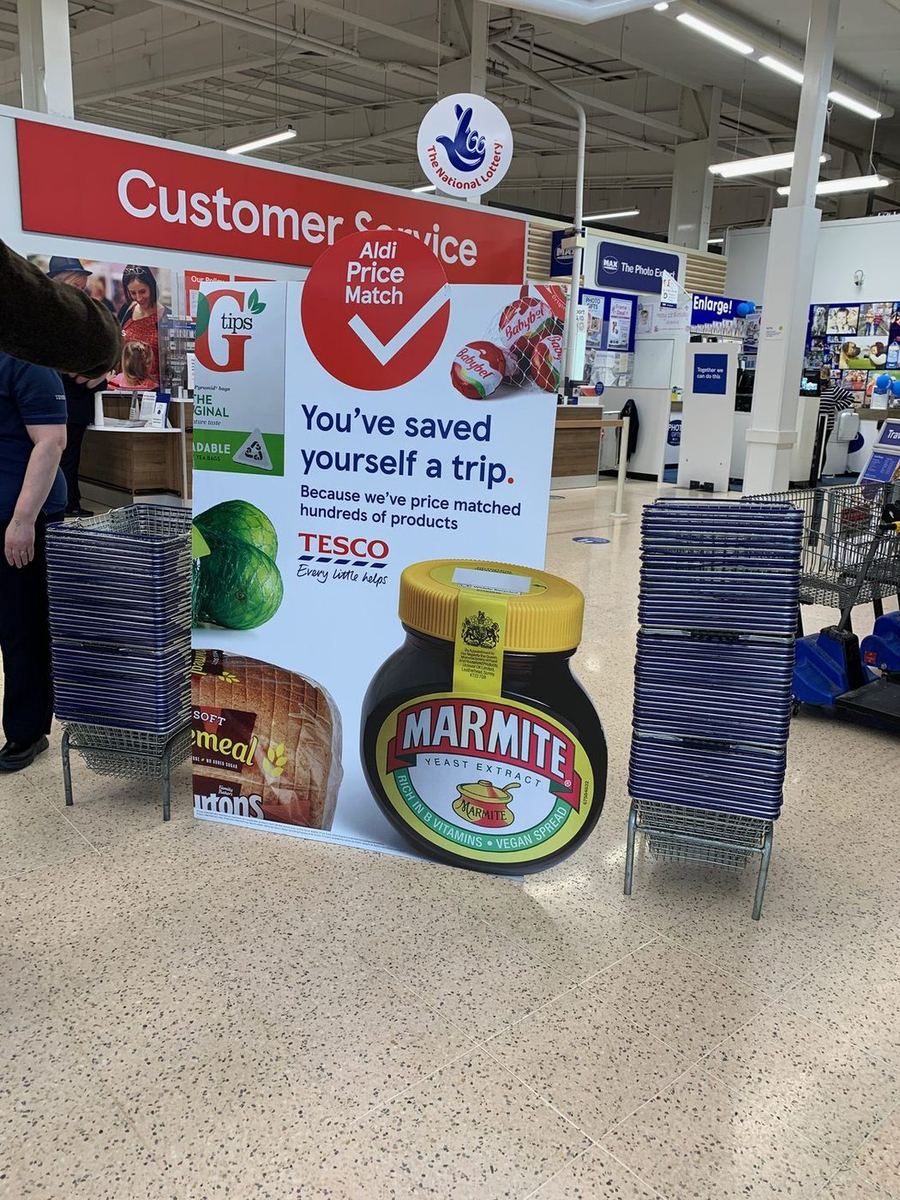
Also in focus was Tesco highlighting their quality credentials; like Sainsbury’s who talk about the Aldi price match and the quality of their own product.
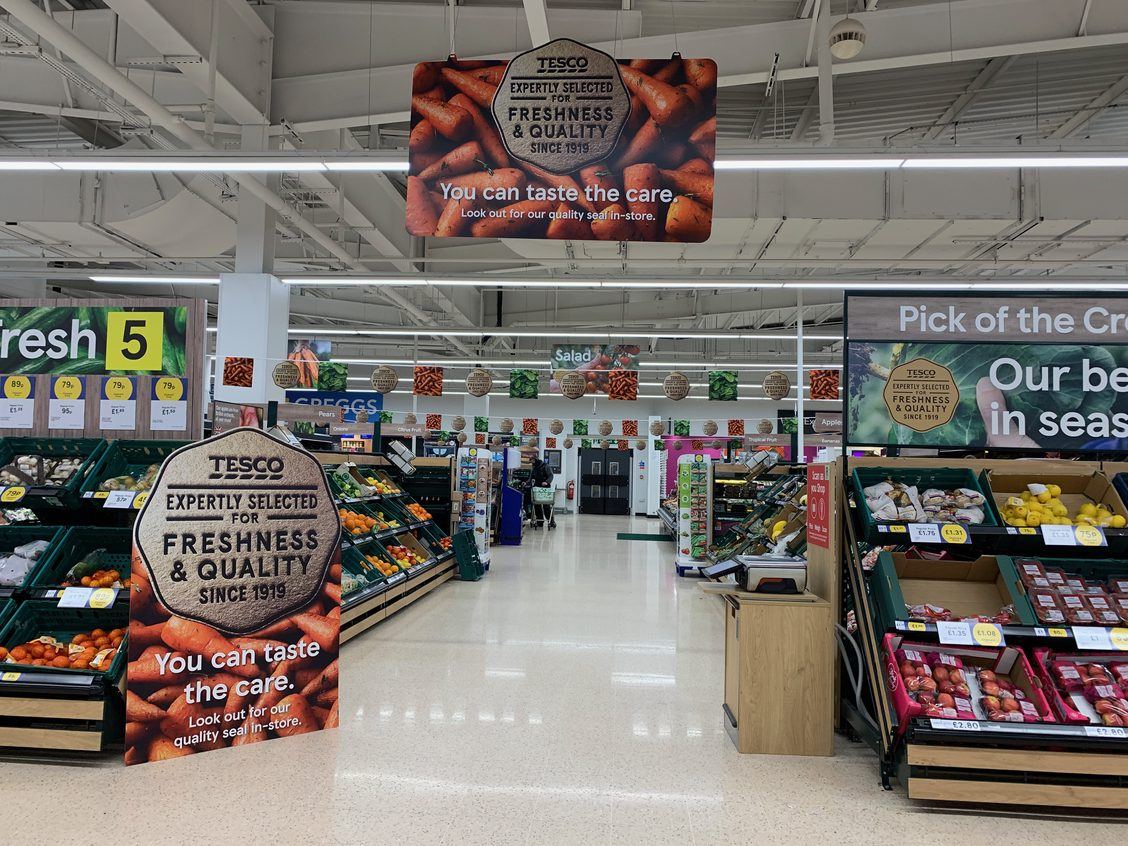
Tesco have also worked hard to highlight their own quality seal whilst reminding customers that it’s not all about price matching value tier products.
Some strong work in Meat too; offering a tangible trade up for customers and a clear sign that Tesco are aiming to grow margin with a wider range of premium lines.
This alongside a greater focus on quality and indeed, directing customers towards meal deals and other ‘bundles’ as well.
Value is never just about price, after all.
 Let us help you with customised market insight and perspectives.Subscribe to this industry email service, today.
From the Grocery Insight newsletter archive, first sent to subscribers on 1 March 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.