Week 15 in stores
25 April 2022
View this email in your browser
Week 15(at least i think it is?)
A warm welcome to “a few things we spotted in stores this week”(*)
(*It’s actually last week) but still, it is relevant and part of a new feature for you, as dear readers and subscribers to our retail newsletter service.
The aim of this email is to highlight things that are occurring in stores, what we see and our thoughts on said observations.
Our clients benefit from our observations on a periodic basis and we’d like to extend the same service level to you, so consider this email as an opportunity for us to showcase some of our thinking, too.
Of course; our emails are designed to help you keep a track on what’s occurring in the market and everything within.
But as we aim to expand our reach - Did you know that we have an image platform that features every single image we capture, split by retailer, every single week?
Not just that; but we have over 60 seasonal events collated too! These are split by relevant sub category too. So you can review Easter Eggs, by year. Or Mother’s Day Floral, even.
Subscription models can be entirely varied and we’ll even help pick out the best imagery for your requirements!
See more of our best in class image platform.Grocery Insight has a team of 3 (self included) who are out visiting stores every week and amongst the 8gb or so worth of images that we collate, decompress and use to demystify retail for our clients…
But there are numerous gems that we collate, that I want to share; to showcase the nuances that make up the retailing space, every single week.
So here we go. The good, the bad and the ugly of retailing.
1. Westminster ExpressWe were in London just before Easter and it was great to be back, given COVID and all that has gone before that.
There is a lot to look at from a retail sense and naturally the checkout free options were reviewed and there was a lot to appreciate from that sense, despite the relatively soulless experience that Amazon and Tesco gave.
The challenge remains that there isn’t an end point for the customer, so you just wander out.
It works well in London but it’s hard to see how it would ever gain traction on a larger scale given the costs to set up.
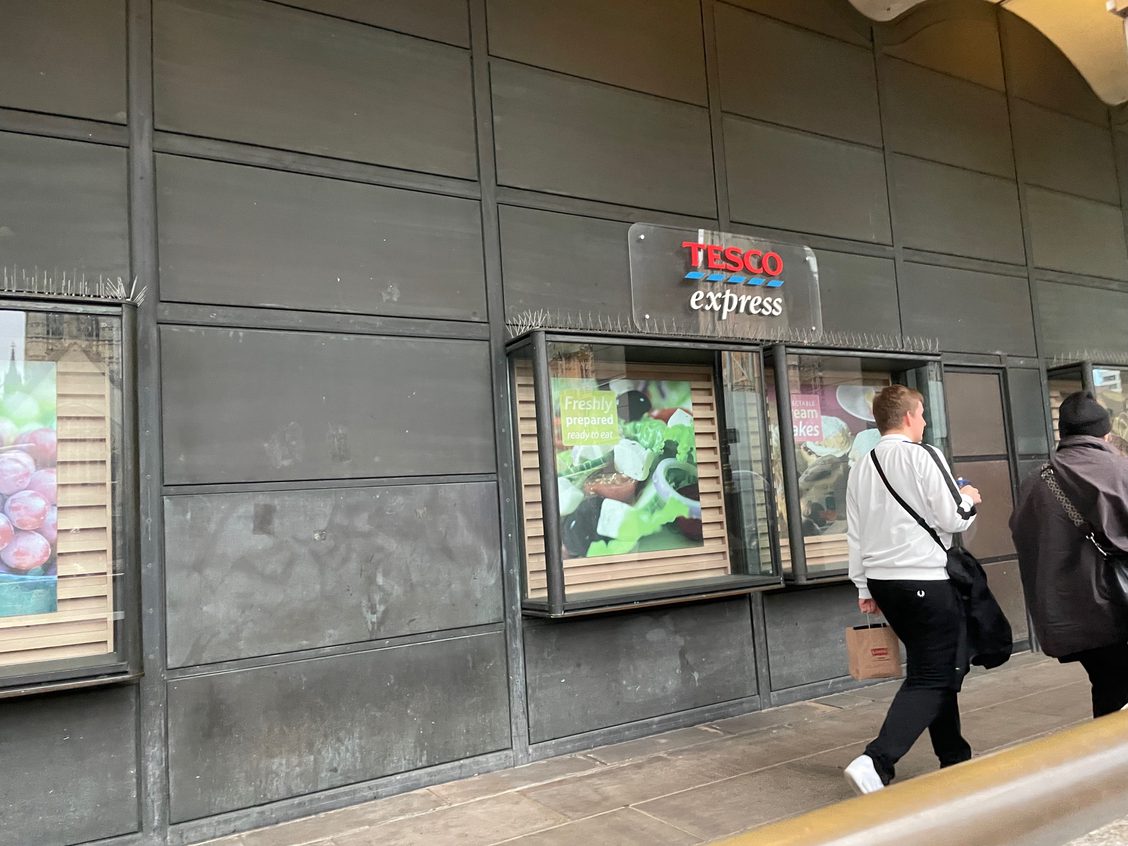
That aside - Westminster Express (a tiny store but very busy near the excellent Westminster tube station) featured old, old signage which was baffling, given the number of people who must walk by the exterior of this store every single day.
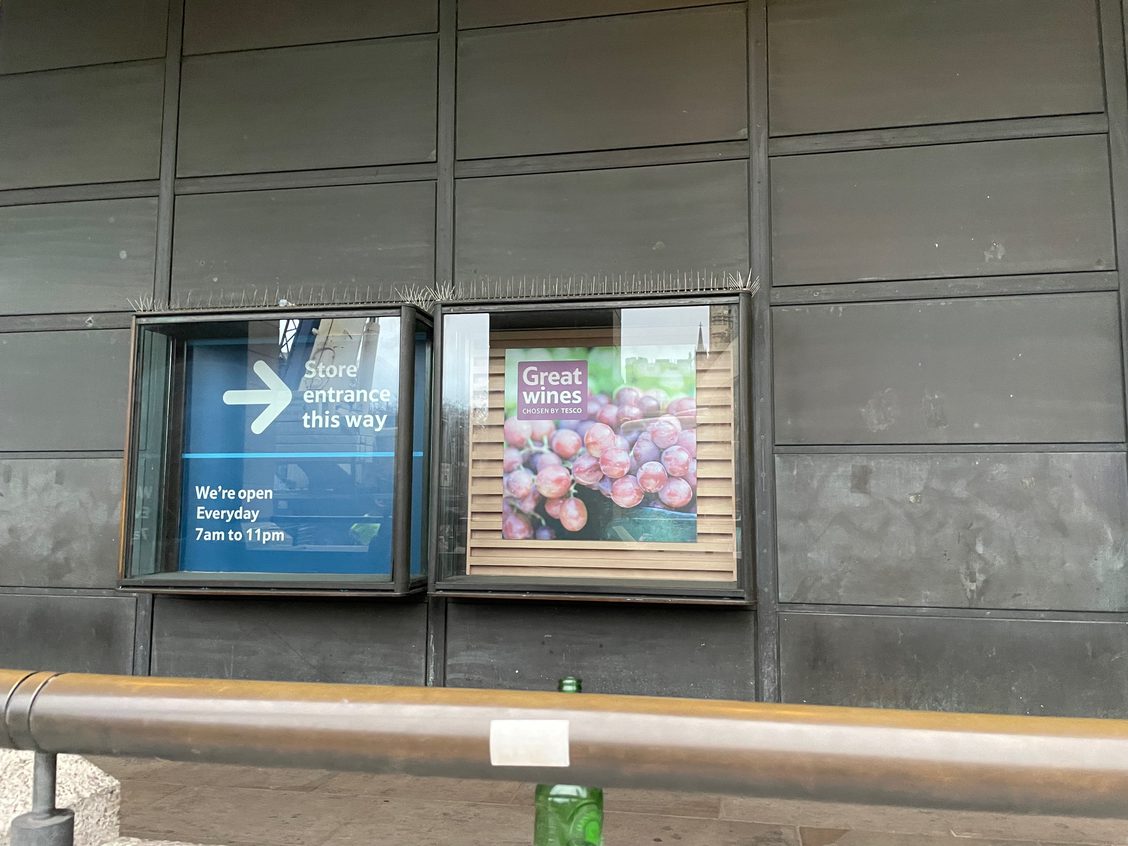
Baffling.
Some may say, Steve, no one cares as no one looks at the signs.
If so, why bother siting any signage there?
 2. Where is the value?
A: Everywhere.
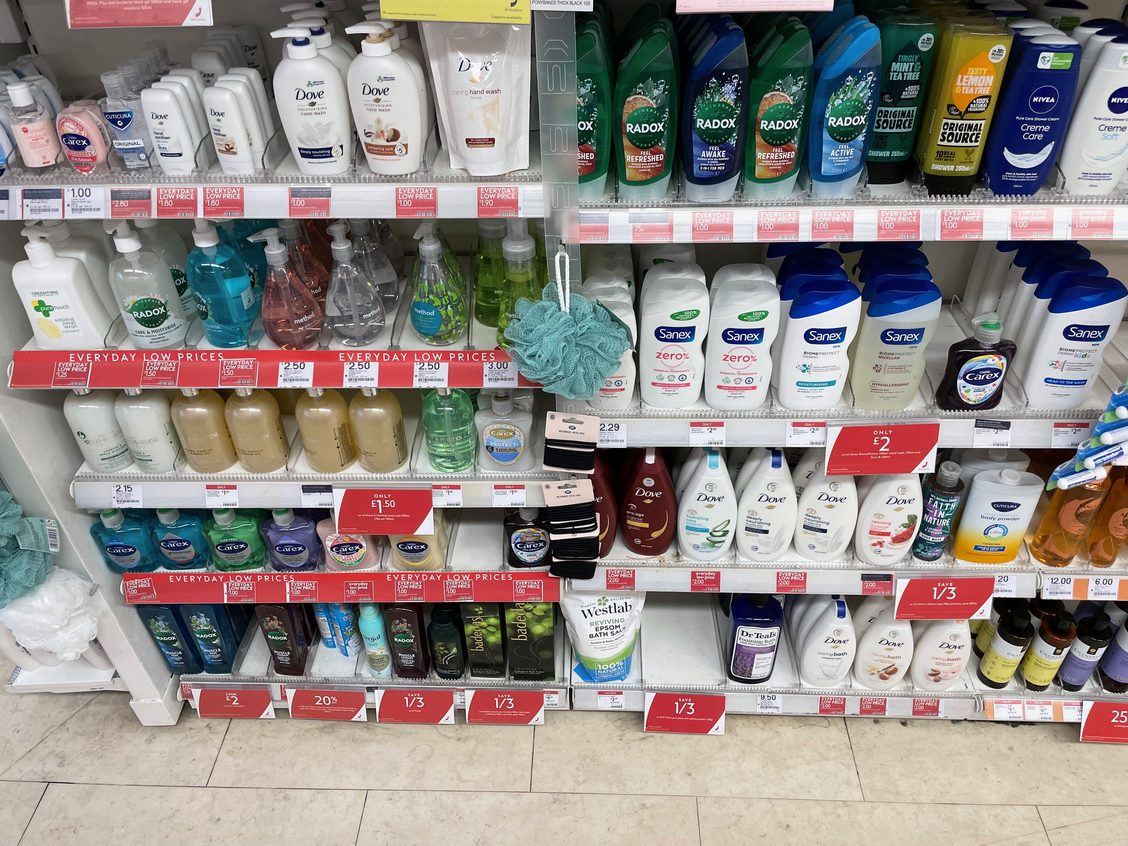
Entirely missing the point on a recent Twitter interaction about the mixed currencies of promotions in Boots.
Now Boots, I am going to do a write up for as they should be like the nation’s neighbour, the one who you go to for a cup of sugar, or a plaster, as they have everything and are near enough, everywhere.
As it is, they’re horrible to shop in, too much choice, confusing promotional architecture and are rarely well run stores.
Ironically whilst appealing to everyone, end up appealing to no one in particular.
Rules of the thumb (from me, at least)
i) EDLP (everyday low price) should never be undermined by a promotion elsewhere in the fixture.
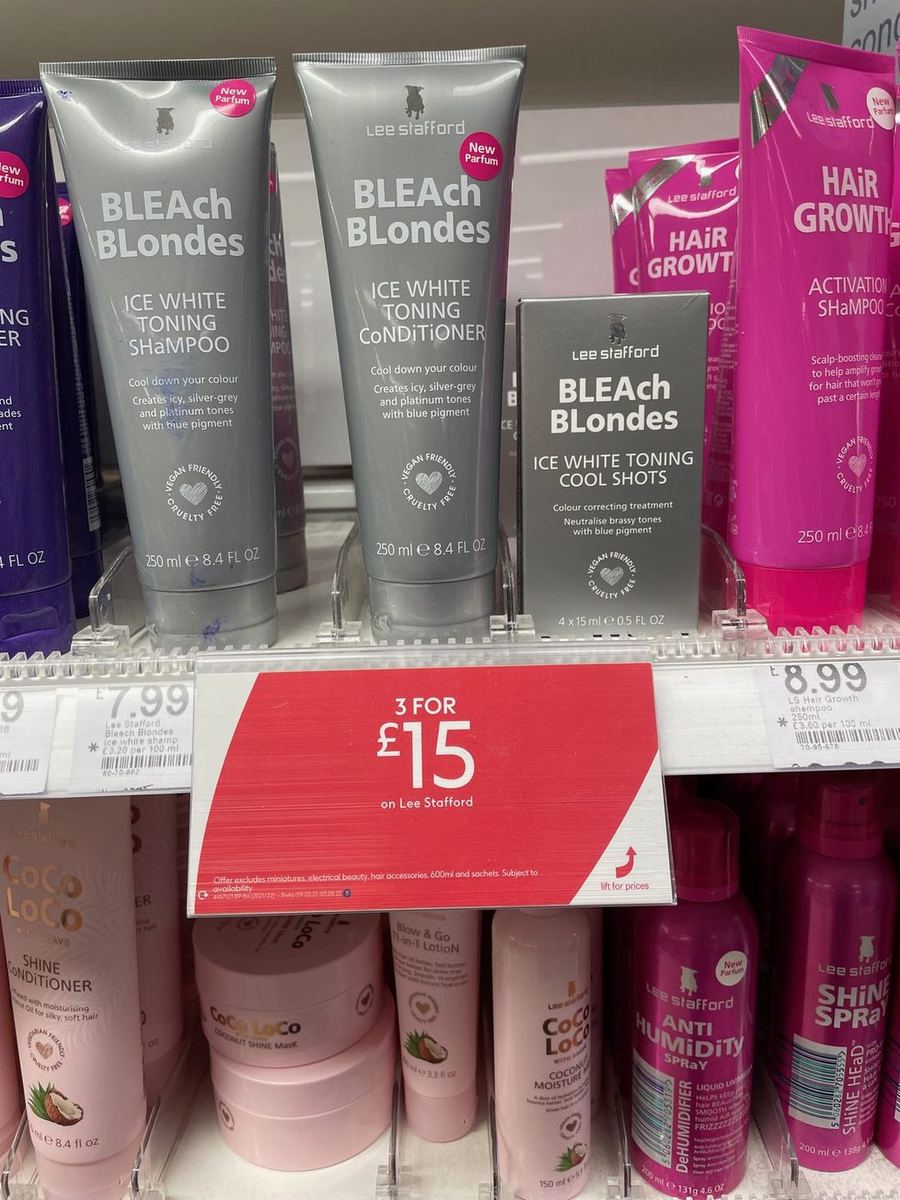
ii) You can’t mix currencies, either use “%” or “1/3” or “£” but not all three, or two as it just creates unnecessary confusion.
iii) Too many signs then just make a mess of the category.
Instead of nicely competing offers, it becomes the *maths gif* and the customer can be forgiven for thinking they’re being ripped off.
PS - expensive promotions are also questionable. £15 screams out!
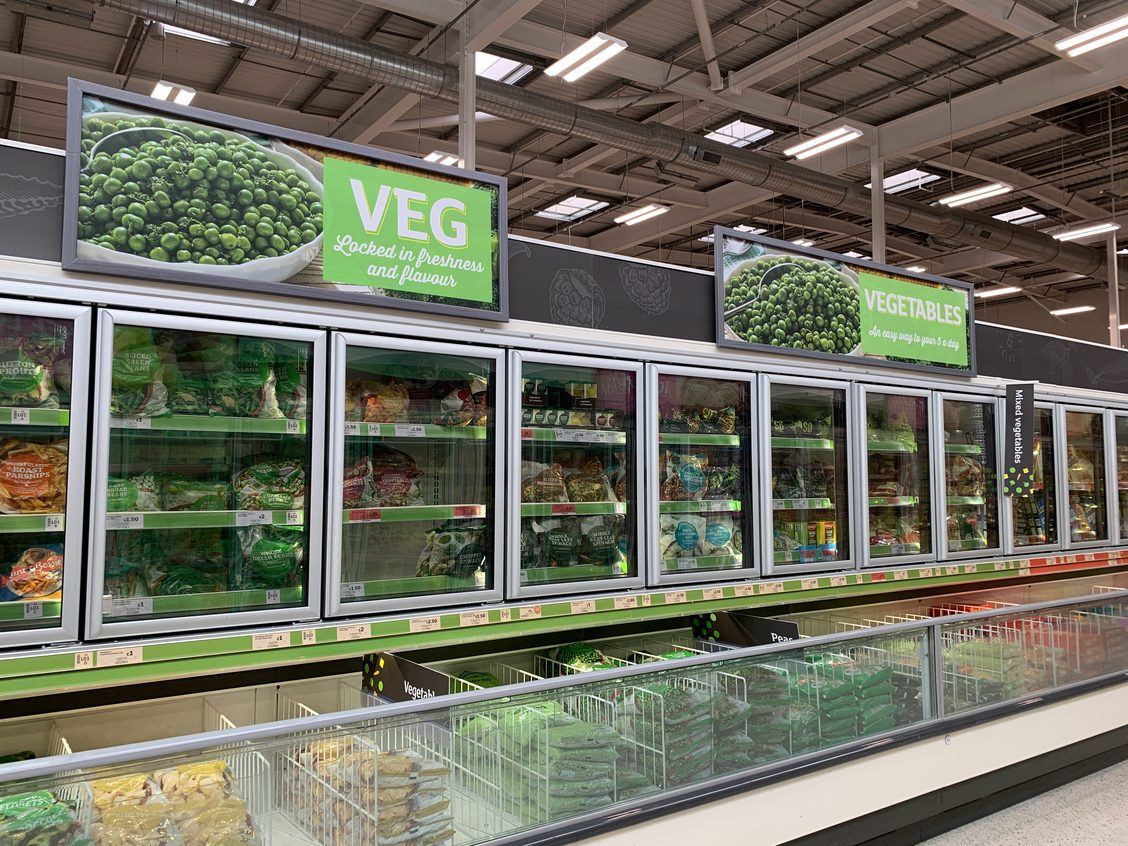
 3. Veg/Veg
Solid work from Sainsbury’s here with their signposting of the Frozen Veg/Vegetables.
Why not have both etc.
 4. Value tier changes
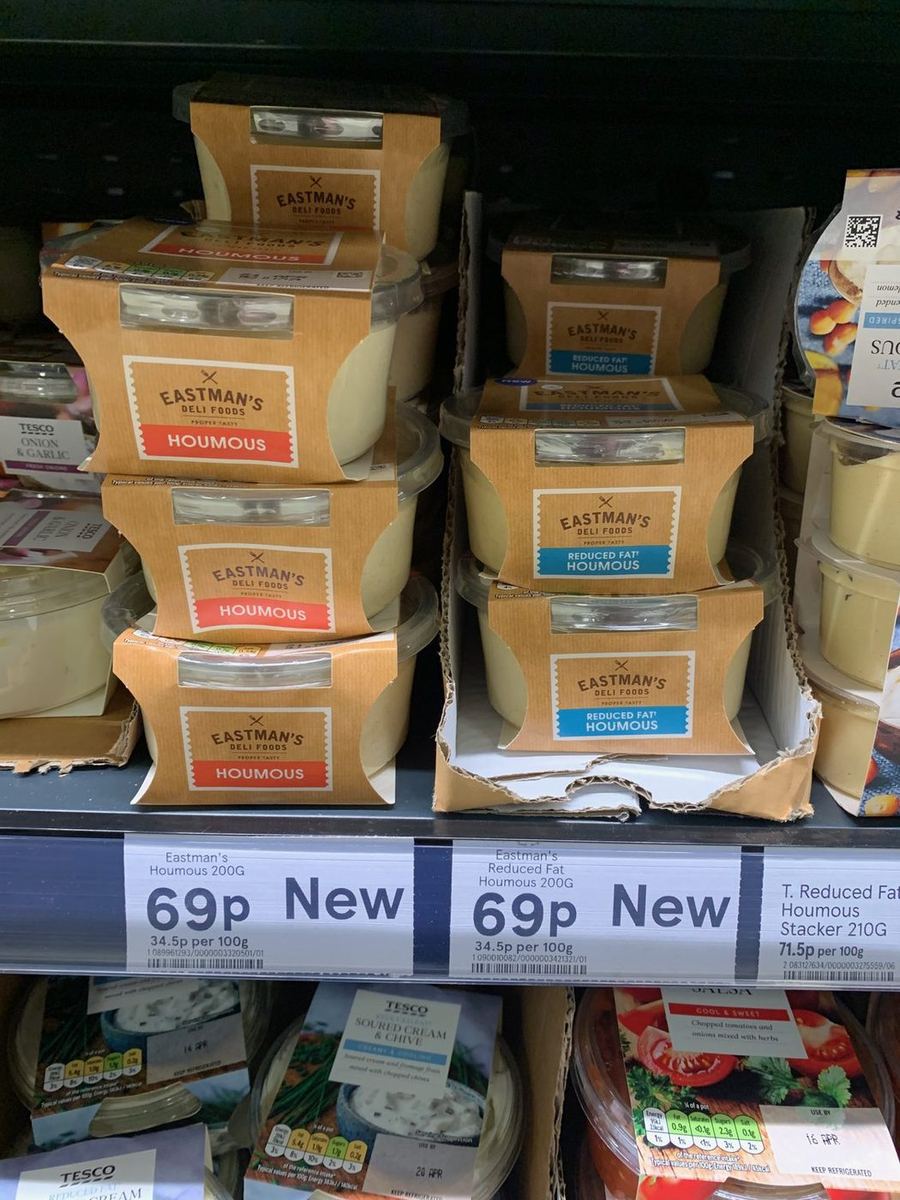
The Tesco moves around value tier, farm brands and the rest has left them in great shape to capitalise as the consumers struggle with rising prices, being a beacon of value for consumers up and down the land.
However their work on value tiers and the various sub brands has been extensive and continues apace, not only are they adding more mid tier products to Aldi price match.
But other products, formerly classified as value tier (Boswell Farms Mince e.g.) was disbanded and the mid tier Tesco product was reduced down in price to what the value tier line had been.
A smart move to consolidate the volume of course, but a risky move.
Customers looking at value tier lines are very budget conscious and notice even a one pence rise in price.
You have to be so careful when changing packs/brands because of the value challenges that brings, even when the price is maintained at the same level.
Interestingly - Tesco have adjusted their core tier to the value tier here and are matching Aldi. It’s a new product and another market for the work that Tesco are undertaking in their quest to nullify Aldi on price.
 5. More value in Lidl
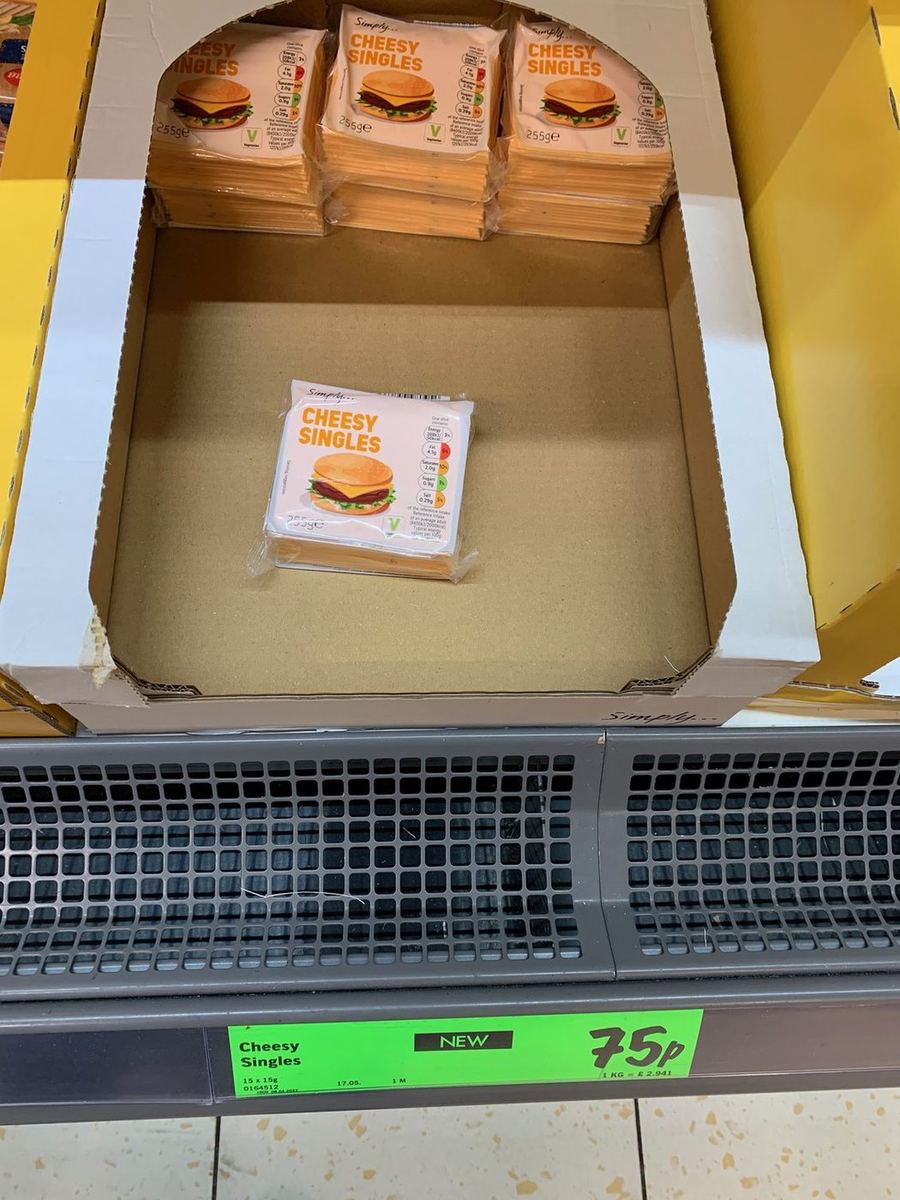
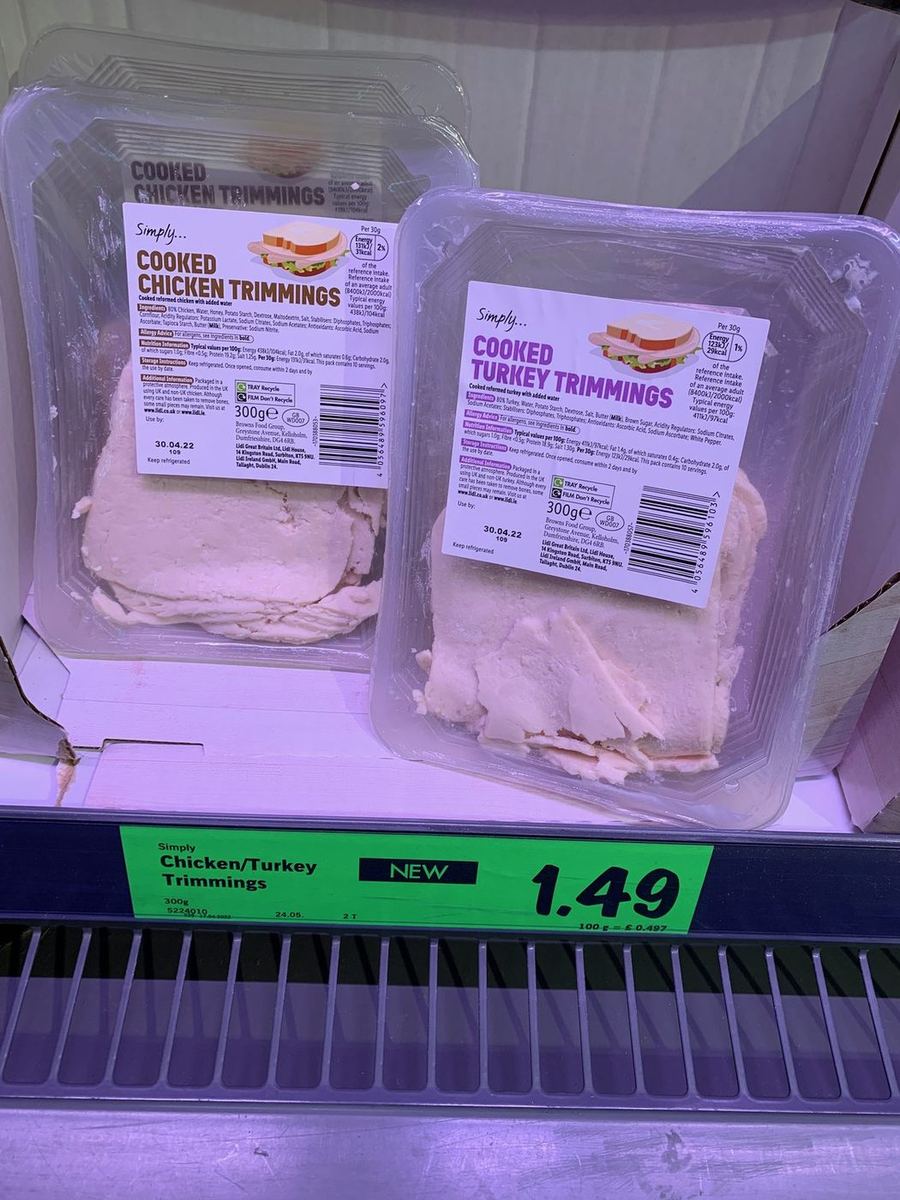
Another notable recent trend has seen Lidl rolling out more of their Value tier products across ambient and fresh foods.
Likely seeing a secondary impact of the work that Tesco have undertaken? Or wanting to do some price comparatives of their own versus Aldi, Tesco and Sainsbury’s?
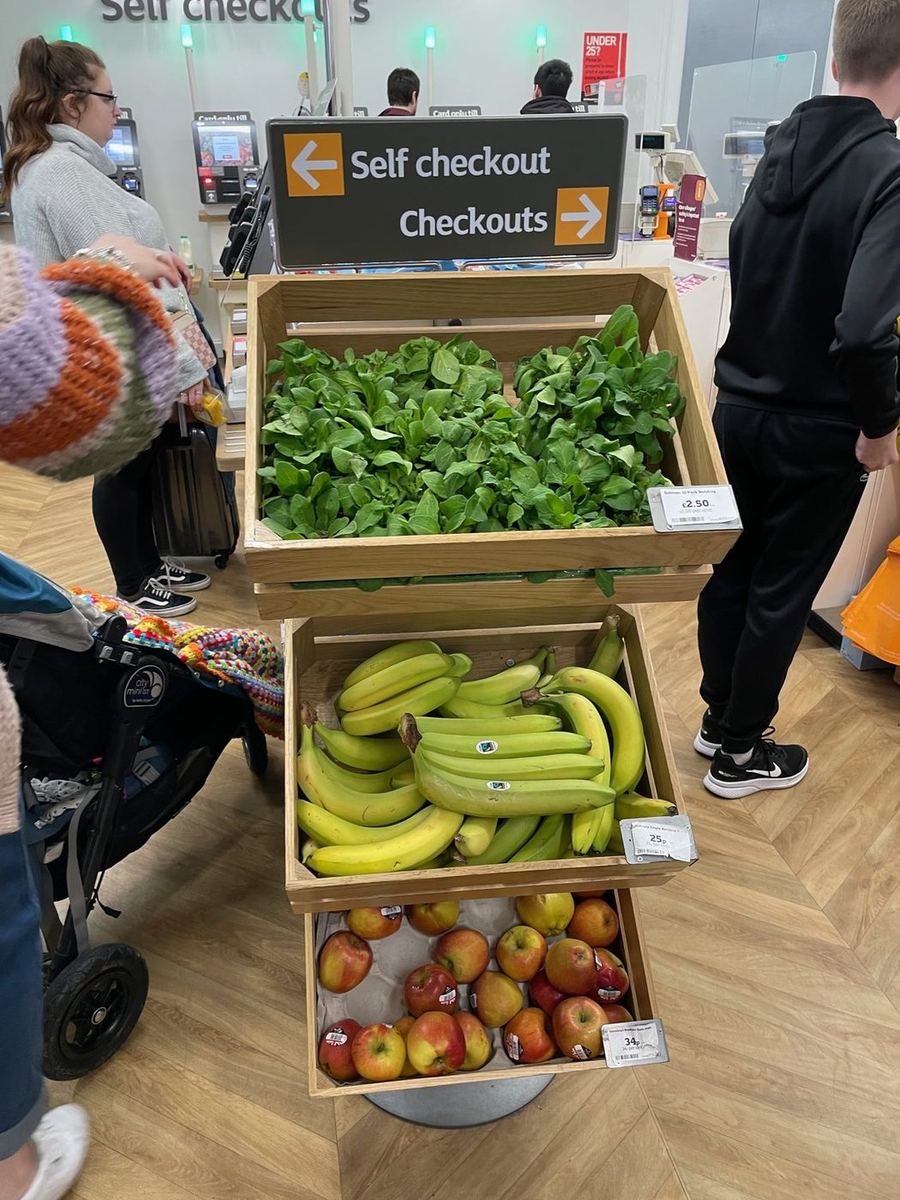
 6. Bedding plants for the train home
One does not expect to see bedding plants in the Produce ‘to go’ section near the self checkouts.
Especially when you consider it’s a Sainsbury’s Local rail station store; commuter central.
Odd ranging here.
 7. A great use of tech
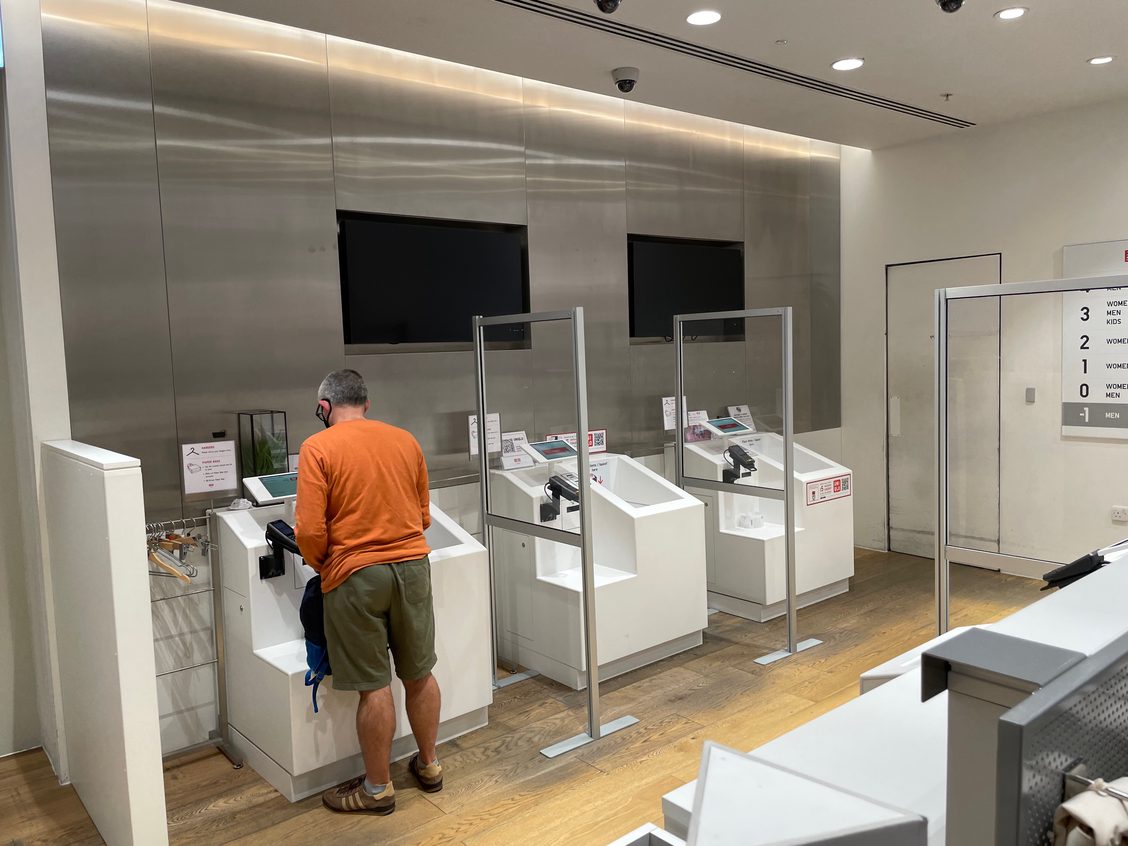
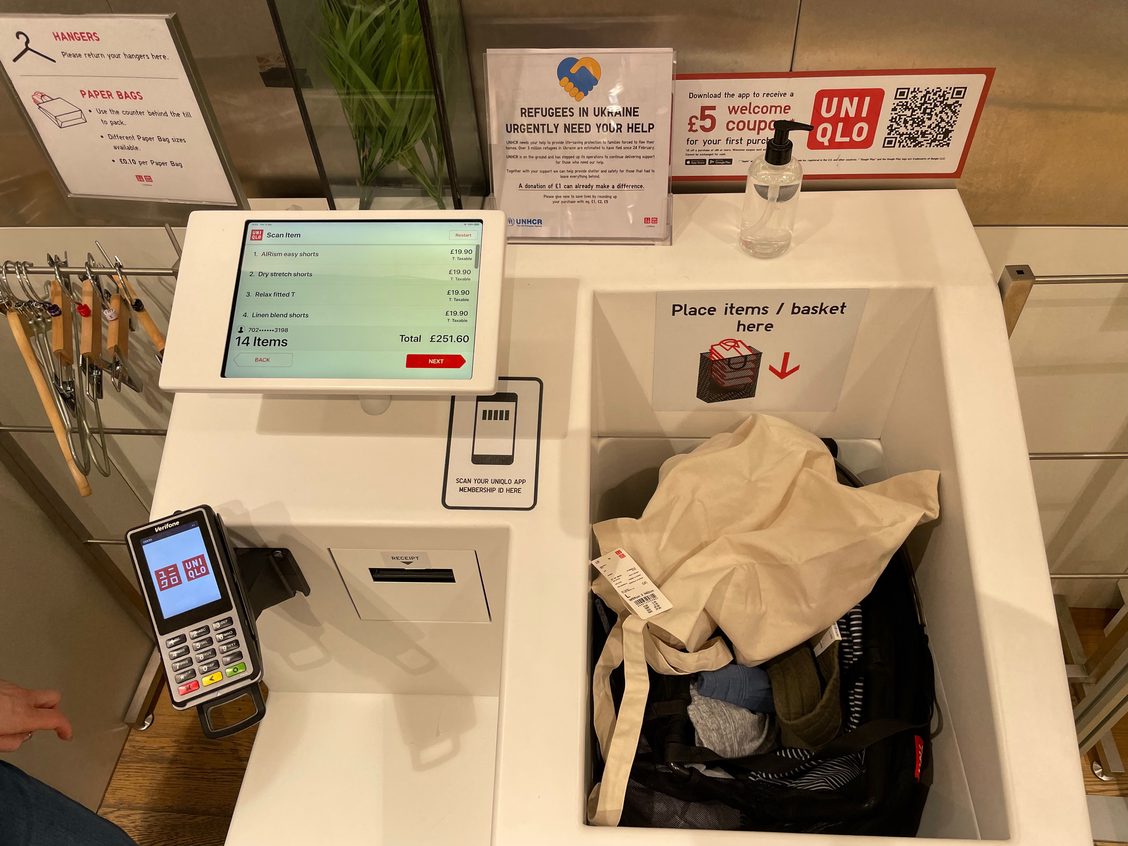
Uniqlo are an admirable clothing retailer and their usage of RFID in their clothing labels is most impressive when you
i) observe their stock checking process which is a colleague waving a handset in the vague direction of the rail.
ii) Use their self checkout and see the products magically appear on the screen before you put your basket in the designated area.
Even when we sense checked the receipt, it didn’t duplicate any of the items and marks such a hugely impressive piece of work.
A true improvement and something akin to this in Primark, or H&M (world’s slowest checkout operation 2019 award) would be majestic.
But it’s expensive…..
That’s all we have this week; a lot of interesting developments and we cover the latest inflationary pressure and market movements in detail over on our subscriber service “retail by email.” which you must check out if you’re interested in retail.
Until next time, trade well.
Learn more about our market insight reporting - never miss a thing again
From the Grocery Insight newsletter archive, first sent to subscribers on 25 April 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.