Issue 473 - Price, price baby
26 April 2022
View this email in your browser
Retail by Email - Issue 473 - Price, price baby.Lots of work on inflation in the market yesterday with price offensives from both Asda and Morrisons.
Both are flagging on a 2 year basis on Kantar (today’s figures, 12 weeks to 17/4/22 have them both -10%) and indeed, both geographically overlap with discounters who are traditionally strong in the north.
Plus that threat from B&M and Home Bargains is also a key element here.
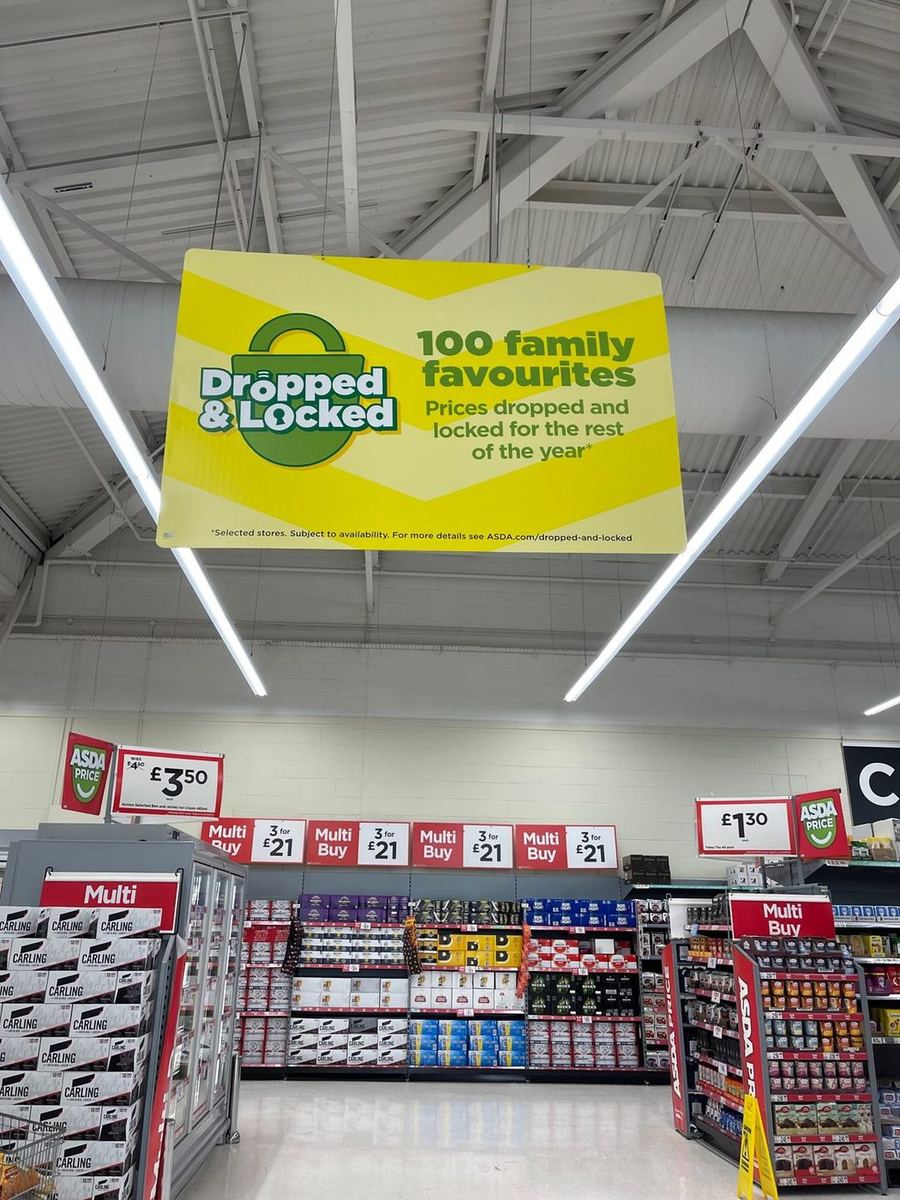
So in terms of the price offensives; customers want price stability and Asda have gone for that with a “dropped and locked” price campaign.
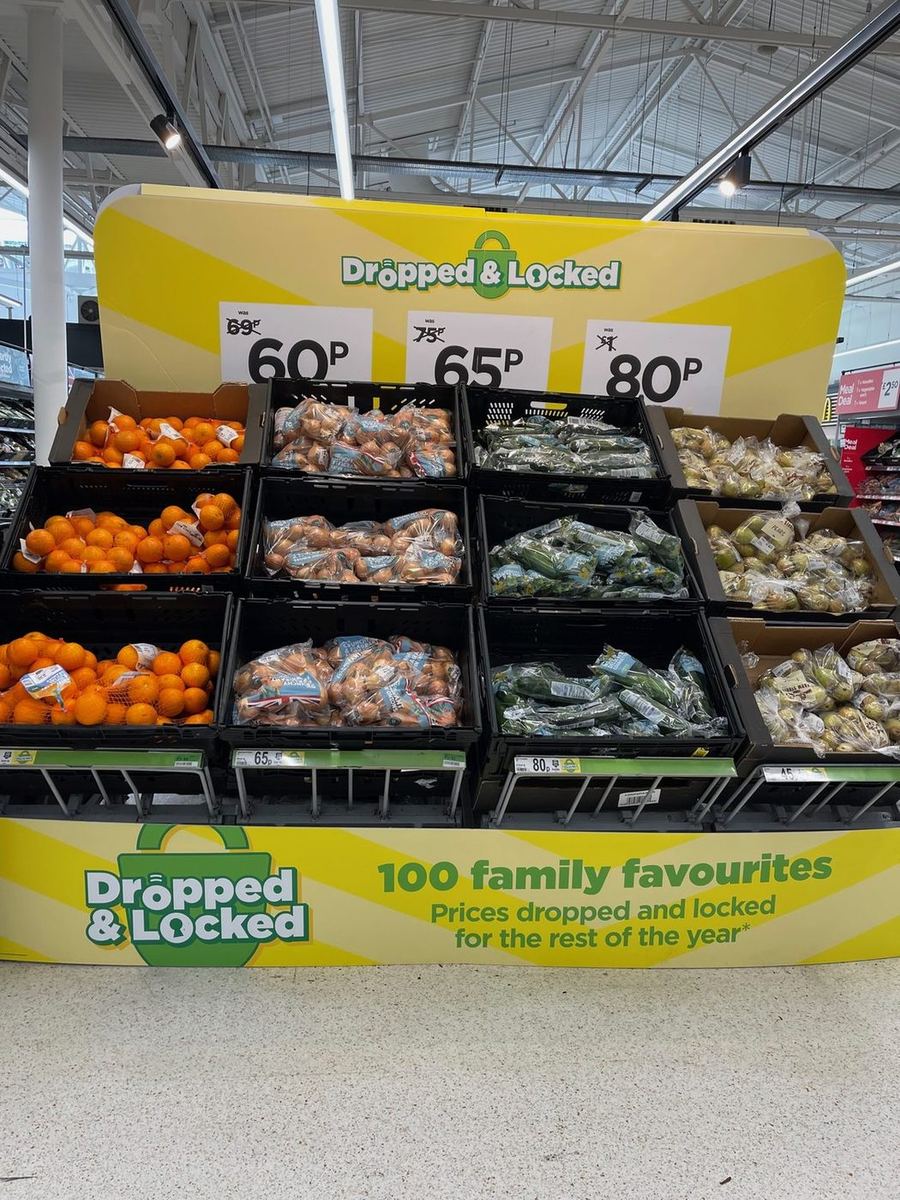
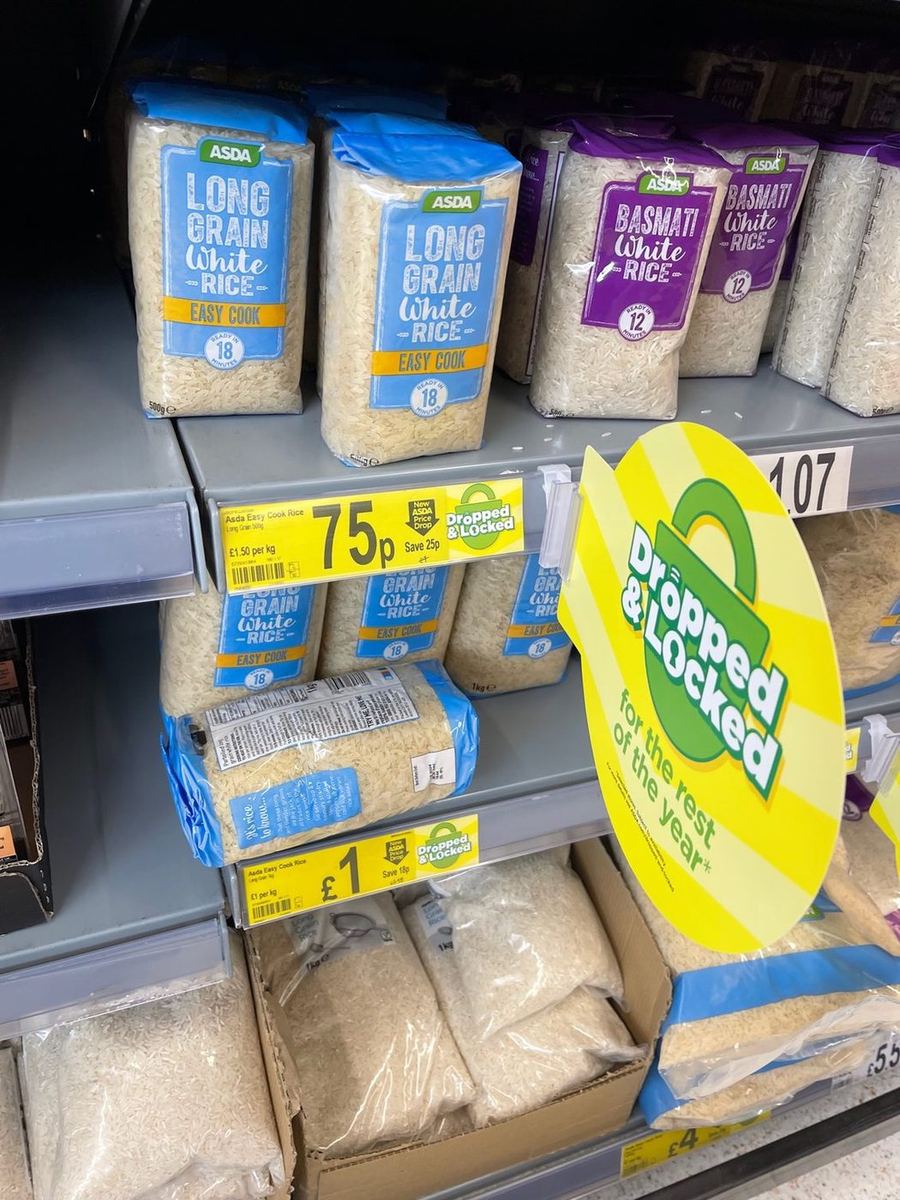
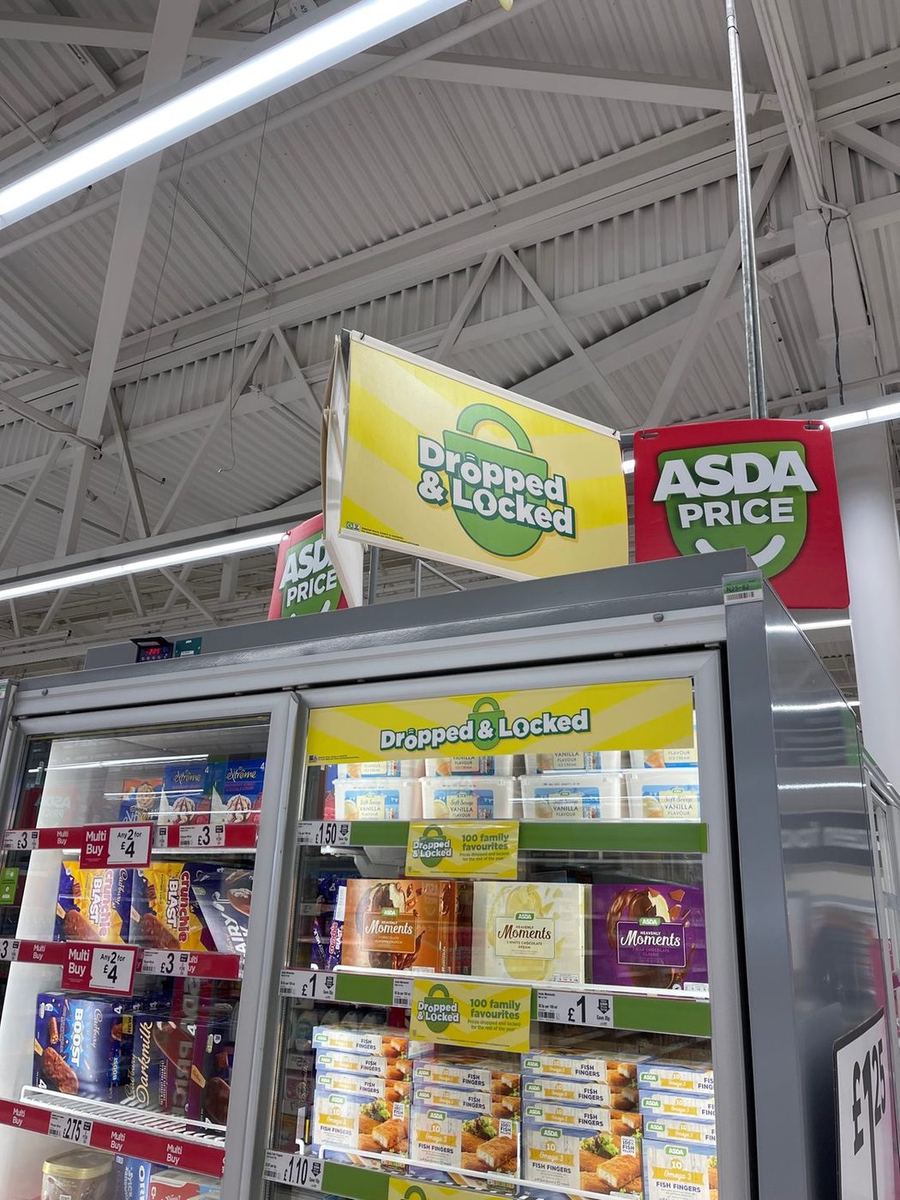
A strong message with dropped and locked; signage stands out well (Yellow rather than their usual red/white) and products are crucial here. It’s a lot of own label lines alongside key staples like Rice, and Fruit & Vegetable lines too.
100 family favourites dropped in price and locked for the rest of the year and it’s likely (for my money) that more would be added, depending on the headwinds throughout 2022.
Of course their core promotional package will remain and Asda must continue to be aggressive in this space too.
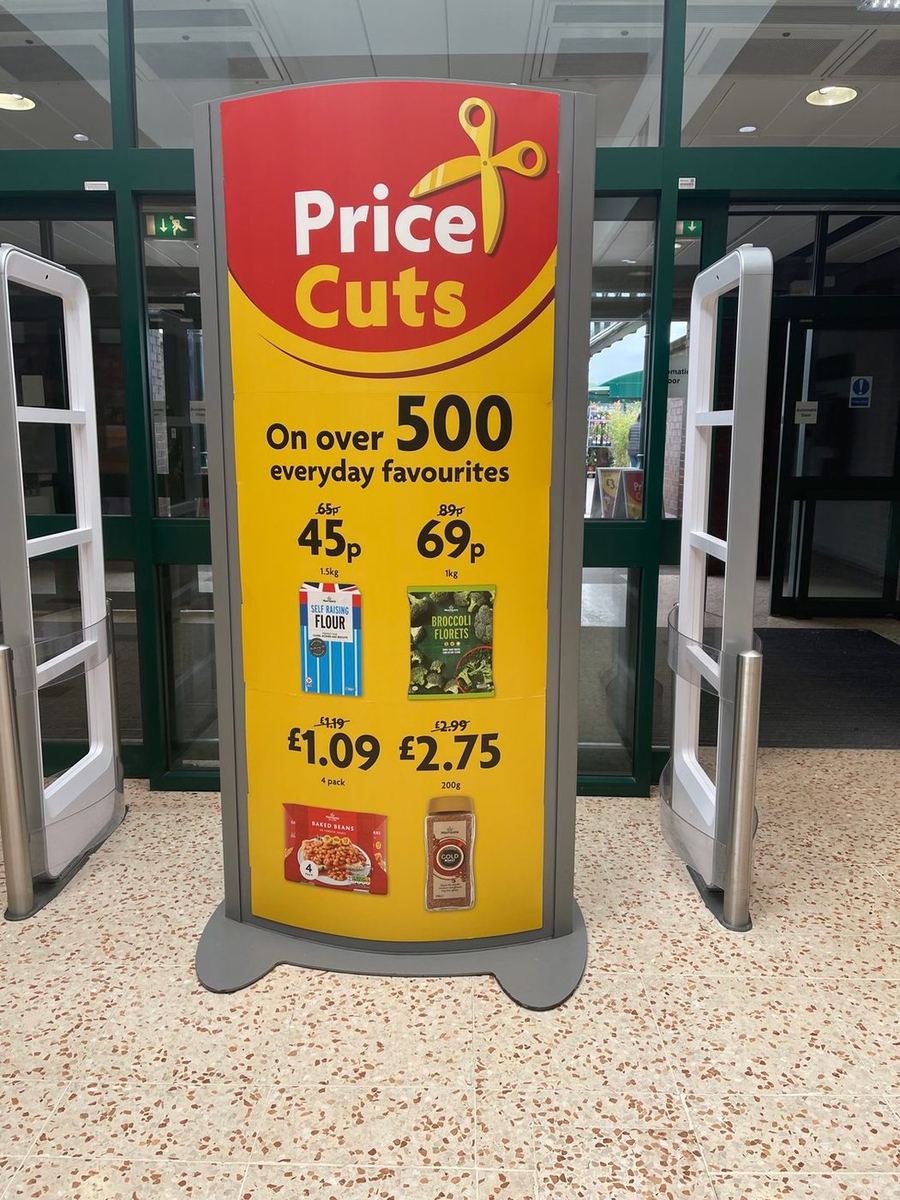
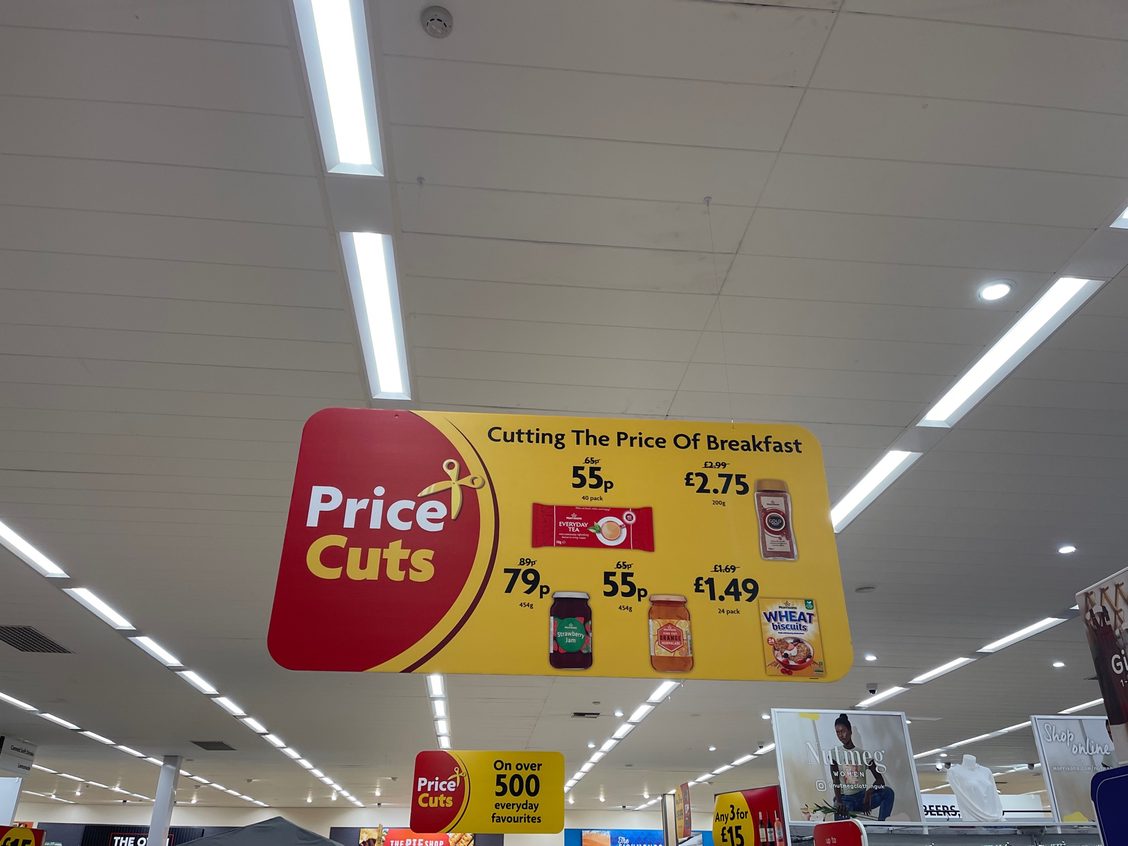
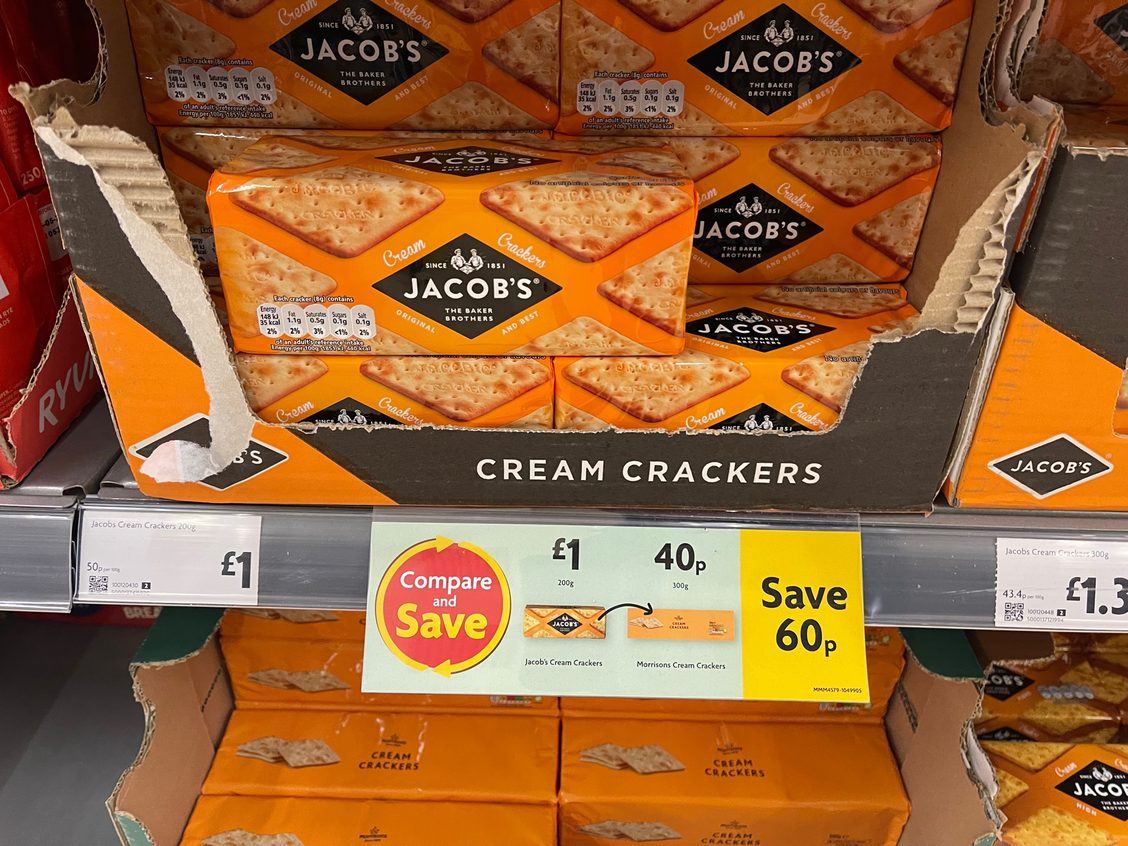
Morrisons landed one of their biggest price campaigns ever with their latest wave of price cuts, in addition, they also landed a compare and save campaign too.
This highlighted the benefits of their own label and compared various branded products to the own label equivalents, with some big savings on offer too.
Interesting moves by both retailers on the price front; of course we know that Sainsbury’s and Tesco are both on the front foot versus Aldi with their price match schemes.
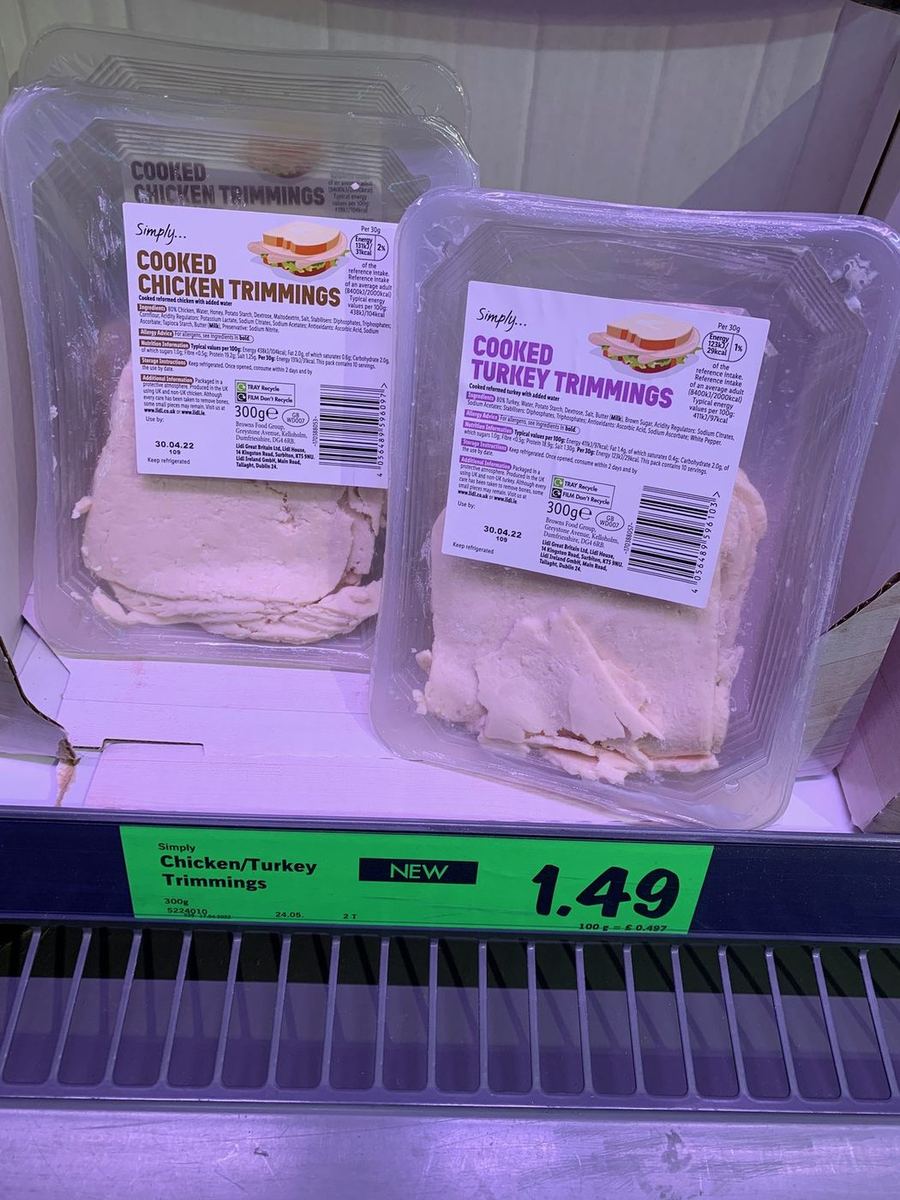
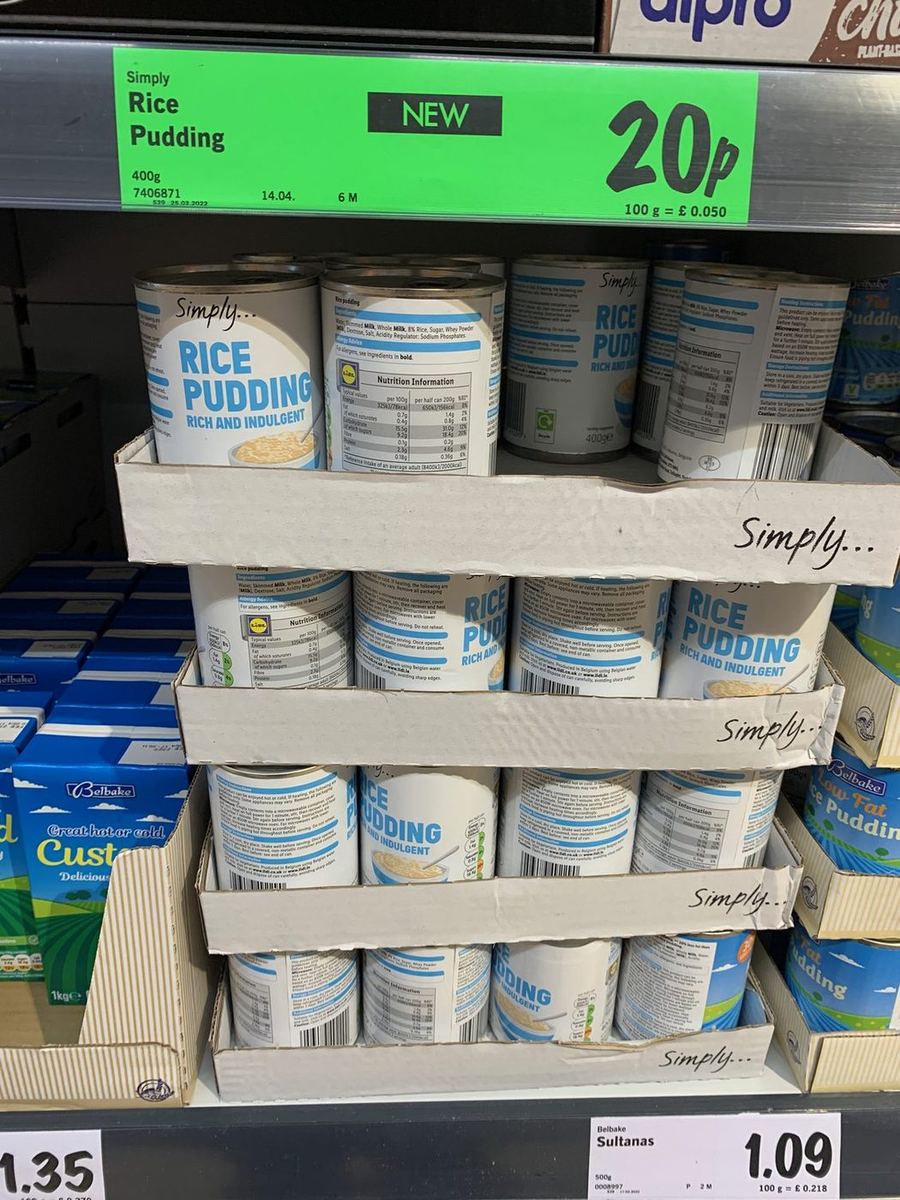
We are seeing other moves in the market too, Lidl, for example are adding more value tier ranges in to their assortments. Planning a move versus Tesco / Sainsbury’s(?)
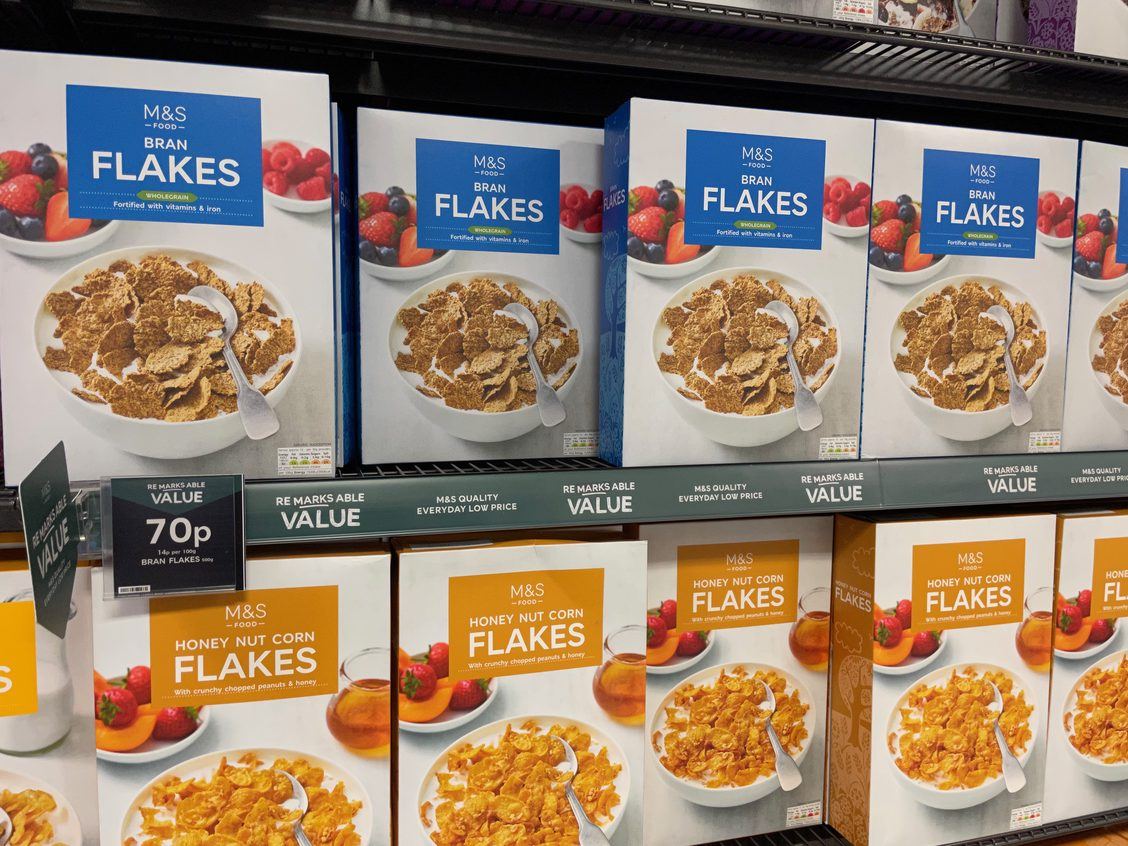
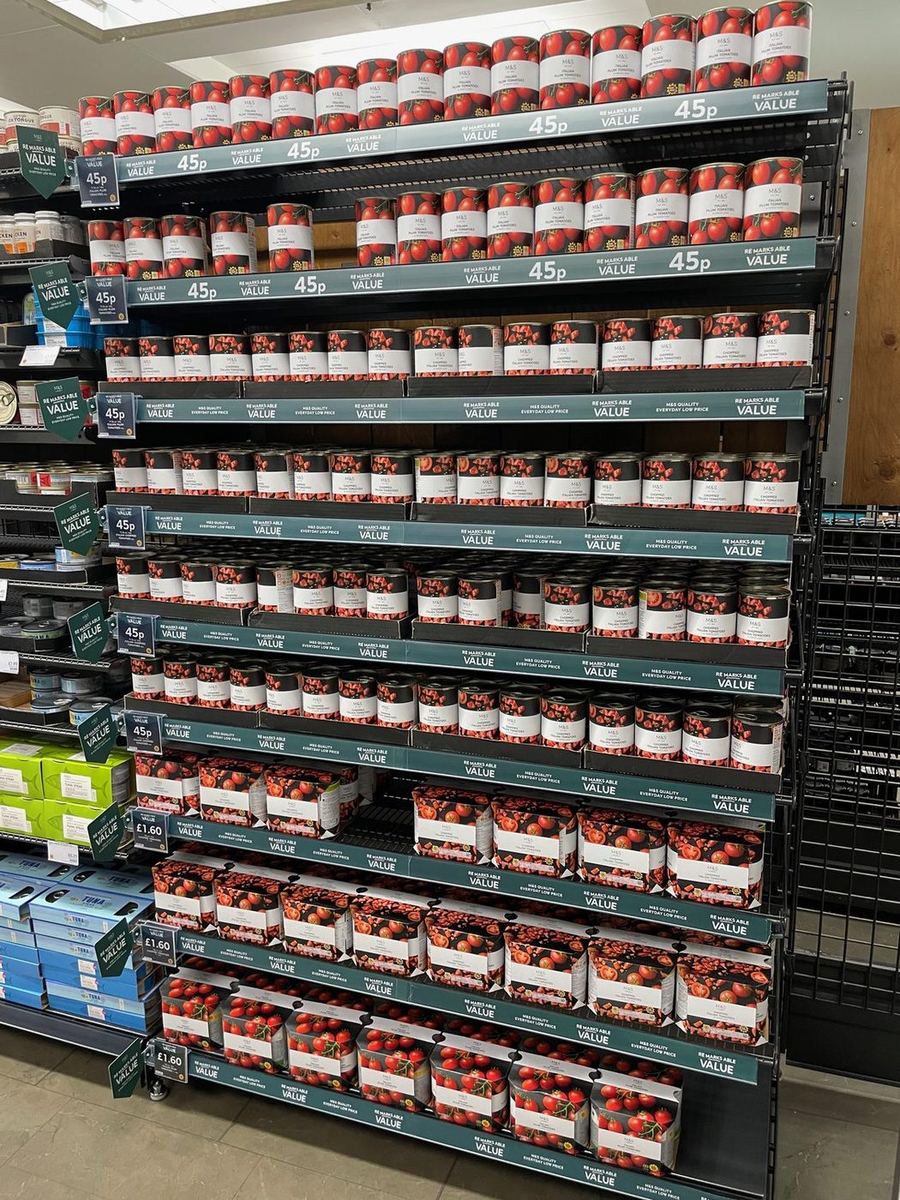
M&S have also been performing very well on Kantar with consecutive share growth, they also re-affirmed their value credentials with a raft of price cuts on their core range of products under “Remarksable value.”
Lots of activity in the market and we’ll only see more affirmations of value from the various retailers as things hot up from an inflation perspective.
Things are getting tight out there for customers and Kantar said inflation of just shy of 6% is the highest since December 2011. It’s interesting because Kantar’s measure is one I really pay attention to as it accounts for promotions too.
So the net, net impact is still high. Which means more pain for.consumers and more battles ahead for retailers trying to keep a lid on inflationary pressure passing to the shelf edge.
Not easy.
Subscribe to our industry leading insight service, today.Want to find out more about our services and the wider retail market?
From the Grocery Insight newsletter archive, first sent to subscribers on 26 April 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.