Tesco full year results
14 April 2021
Enlighten your inbox, join today.
Why not visit our new website?
Just as the Q&A wraps up from the Tesco full year results, our headline thoughts are below:
It is Ken Murphy's first appearance as CEO, and Alan Stewart's last, as he retires as CFO shortly.
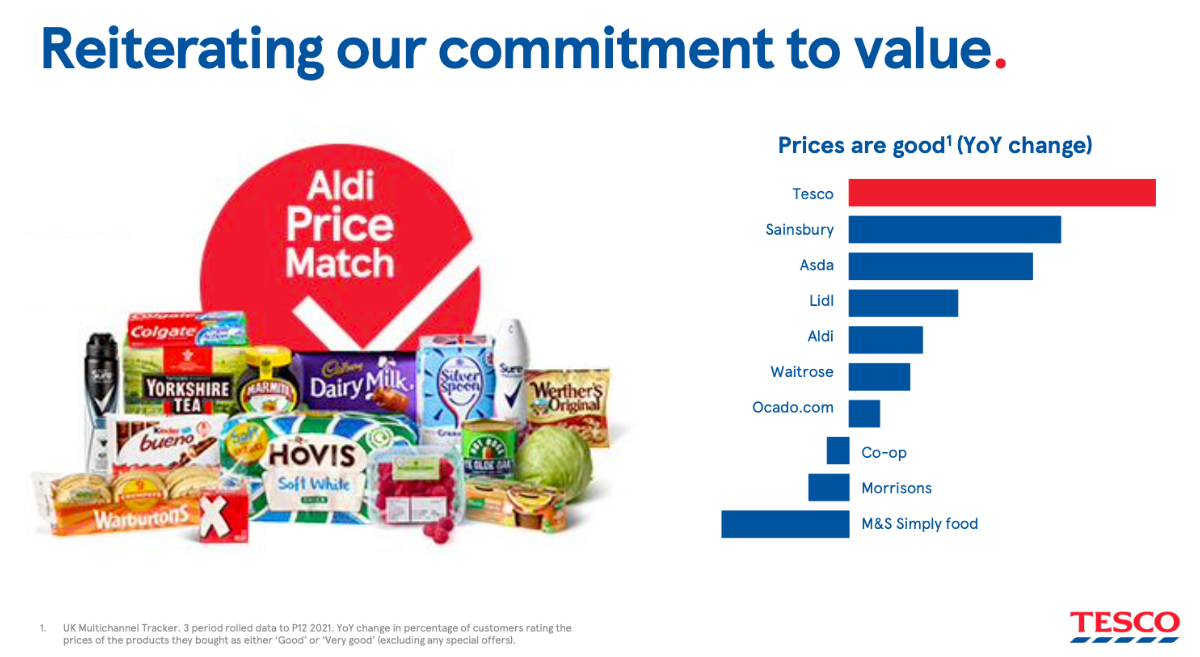
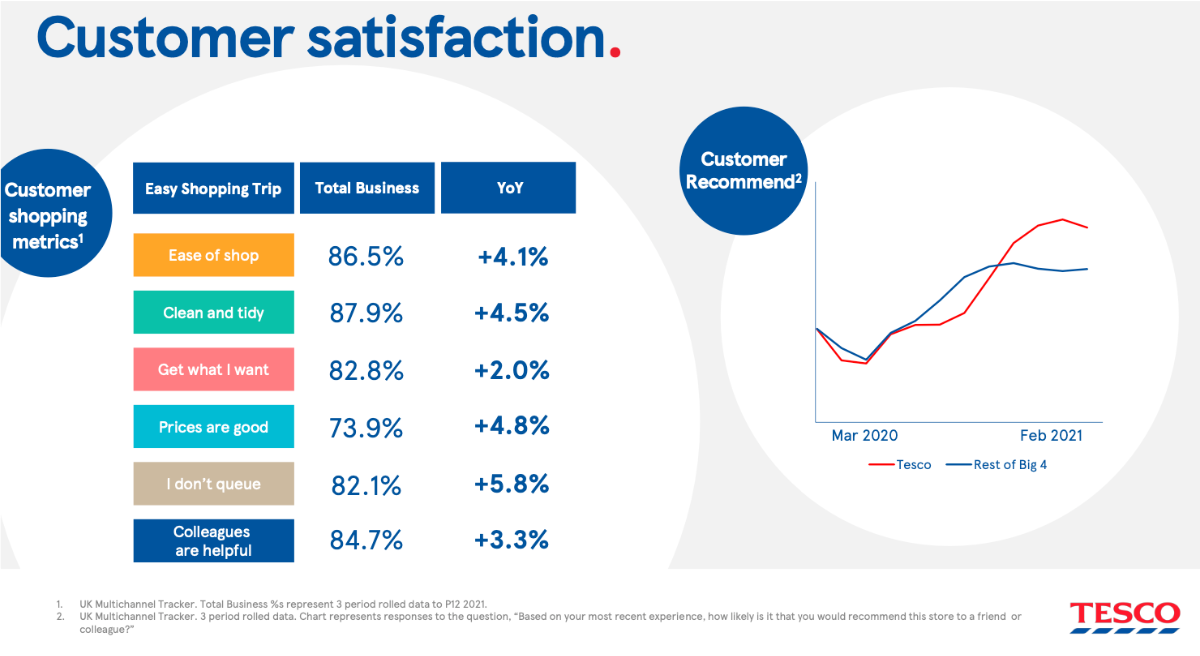
The results were strong, as expected, with a good number of positive figures around customer satisfaction, value was also strong which is very important as customers watched the pennies.
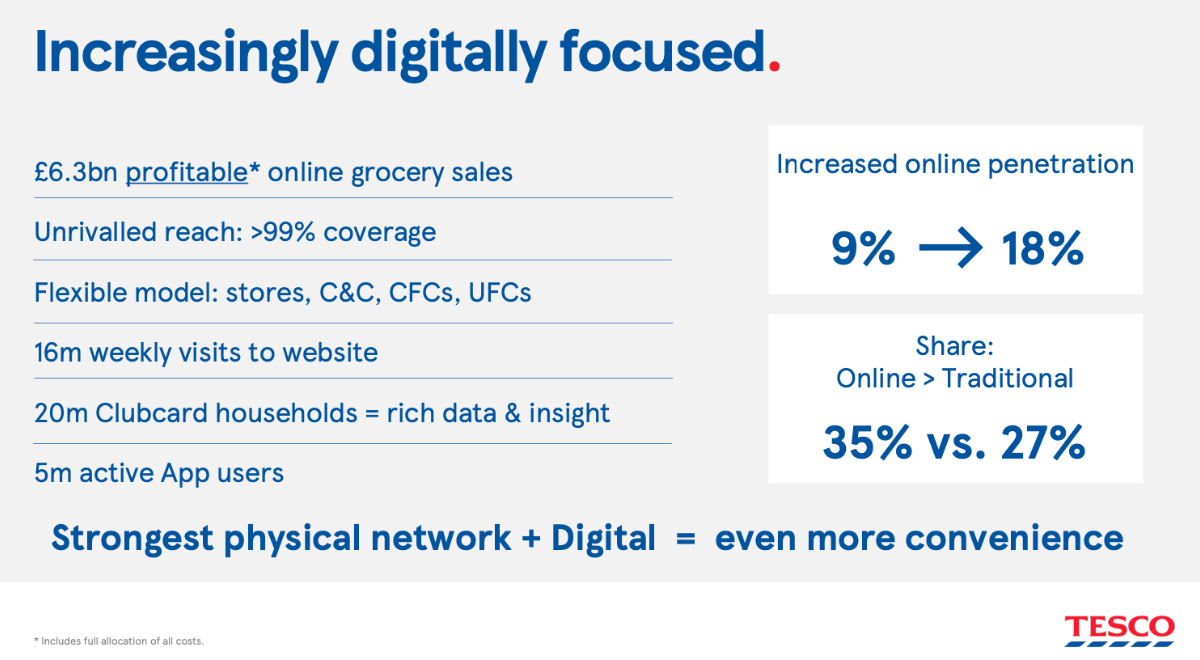
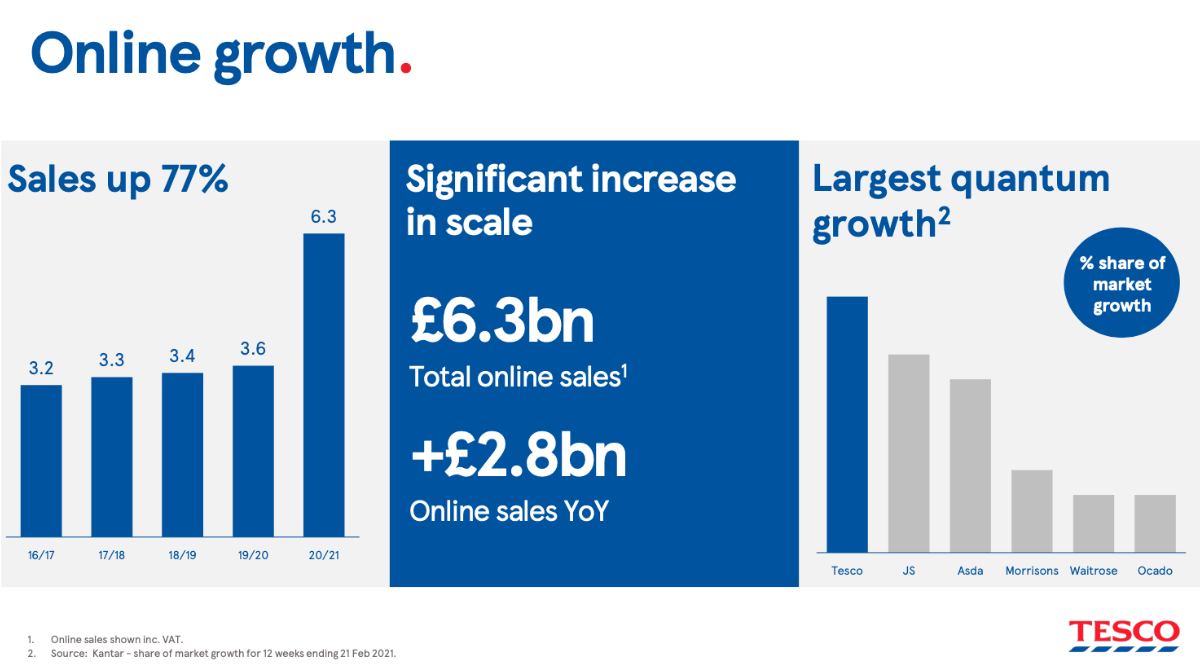
Indeed, online wise - growth is huge and the business now commands £6.3bn turnover of the wider Tesco pie. However, it's still small versus the wider business (£48bn) but, nonetheless, their infrastructure and store network is now viewed as a strength, rather than a weakness.
Lots of talk about 'on demand' services that Tesco are reviewing, Uber Eats for example, offer delivery via Asda and also McColl's stores alongside some independent stores too. Indeed, Tesco are trailing some opportunities here and their Express network would be well suited to capitalise on this emerging trend.
Tesco to behave like a challenger brand is near frightening for the market, as their work with Wicked Kitchen, a Vegan brand, has shown what they can do and also, the wider halo for the business too.
Ken spoke at length about the opportunity with UFC and the data that they're able to respond to an order within 8 minutes, so it looks as though the next 'space race' will be linked to service, who can offer the fastest shop? Fastest click/collect? Order today, be with you in an hour. etc.
The UFC's bring some form of automation and mechanisation to the service and will reduce cost to serve significantly, which aids the profitability, which is good. Tesco online does make a profit, but it's not split out, despite being £6.3bn worth of sales.
They share lots of assets as Ken notes, product file, people etc. So it's hard to do and they don't split out convenience. However, what that profit number is, will continue to elude us. Especially with click/collect only being 25% of the overall order number, meaning 75% are delivered and with their growth being c. 70% - it's still a huge number.
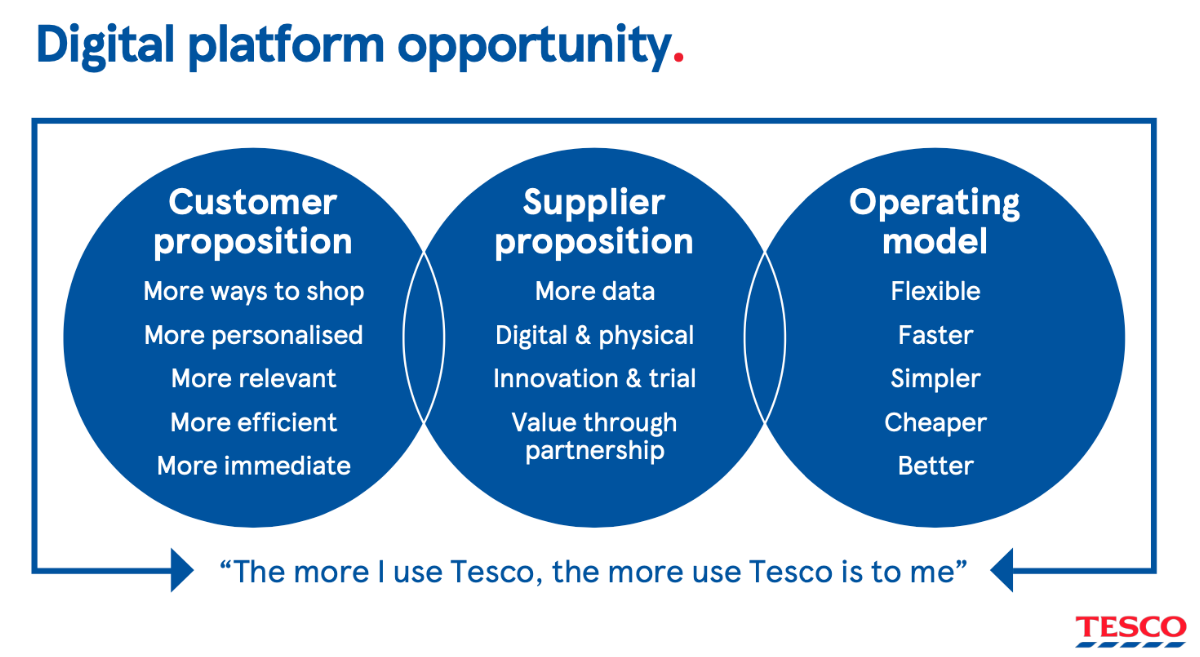
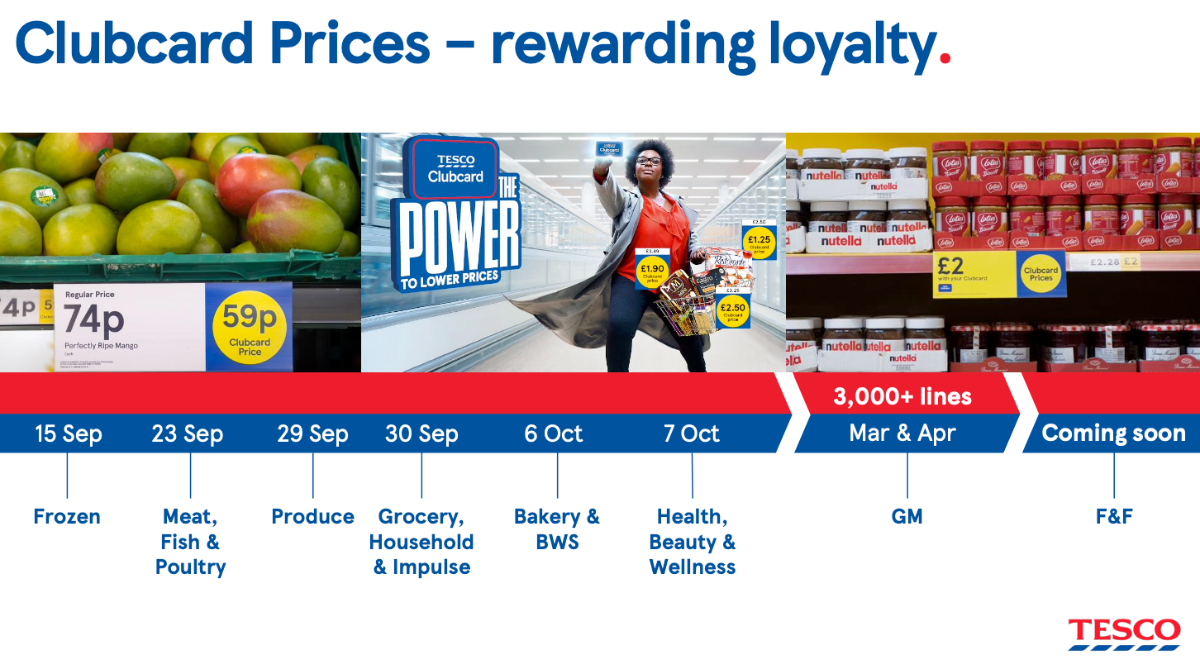
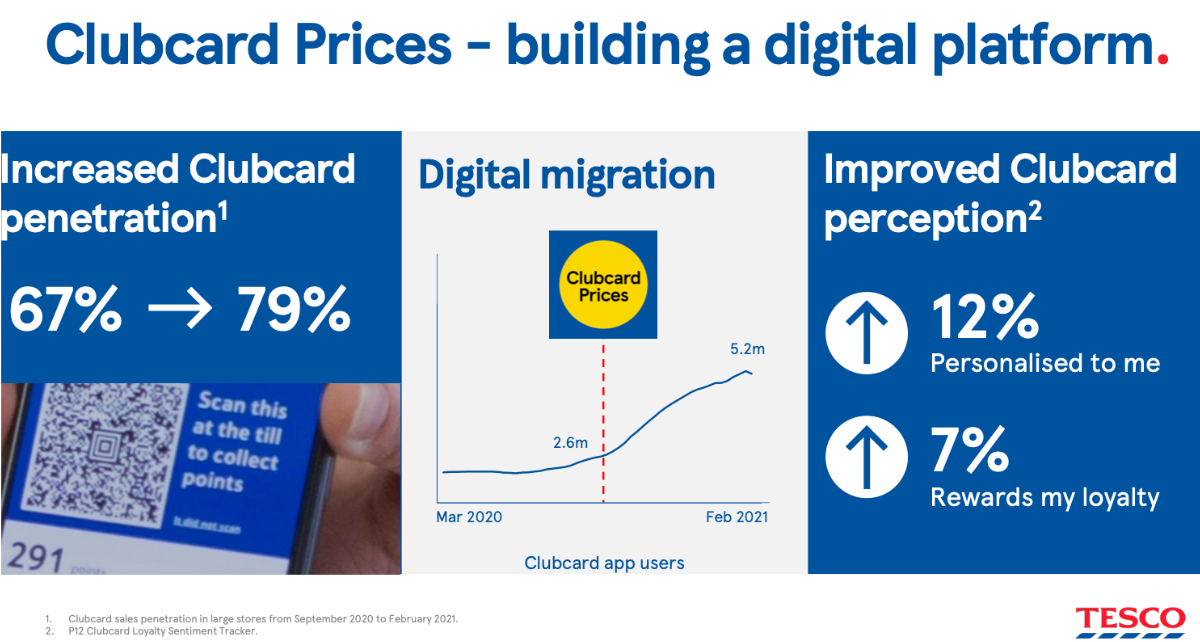
Clubcard prices have performed well; lots of uptake via the app, more loyalty holders and more customers joining the scheme which drives better loyalty data of course, enabling the business to see who is shopping with them, what they're doing and how it all fits together.
Ken spoke at length about market share and needing to grow / maintain the market share given the flexibility it gives the business, so we should expect aggression going forward for sure via Tesco.
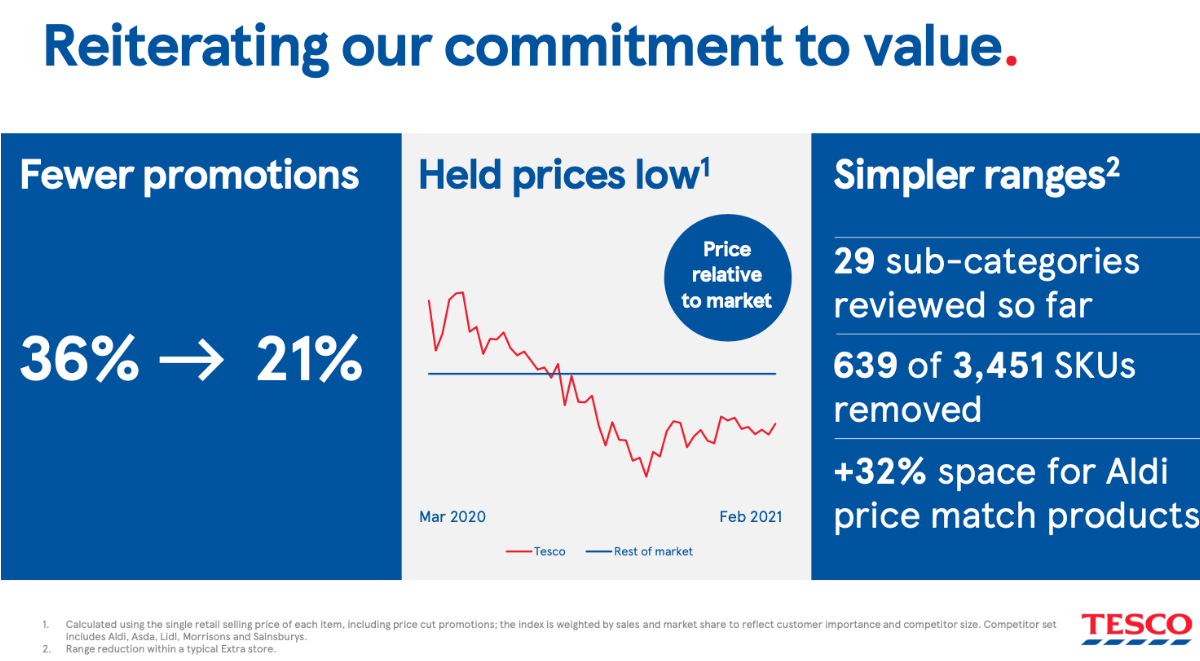
Value is a big winner, Ken Murphy has just spoken about value, price campaigns being strategical beyond 6 months and the Aldi price match has been such a success.
The fact that JS have mimicked the campaign is a flattery he noted, certainly, their share gains versus the market and indeed, internal scores showing that customers are seeing the benefits of lower prices and clubcard prices are positives.
Still inflation in the market of course, that will take time to come through but Tesco have committed to their low prices and continue to do so.
Simpler ranges sees another 18% of products coming out of the range with 29 sub categories visited so far. Fewer deals to 21% was via COVID but it looks as though that may stick as a change for the retailer, Tesco wanted to get off the deals drug and COVID may well have allowed them to do it.
Data flows via Clubcard will improve with the number of customers joining the scheme via the app, in store, to get the discounts. As a reminder, virtually all special offers are now eligible for clubcard holders only. Indeed, even the longer term multi-buys - 3 for £6 on ready meals e.g are now clubcard price only.
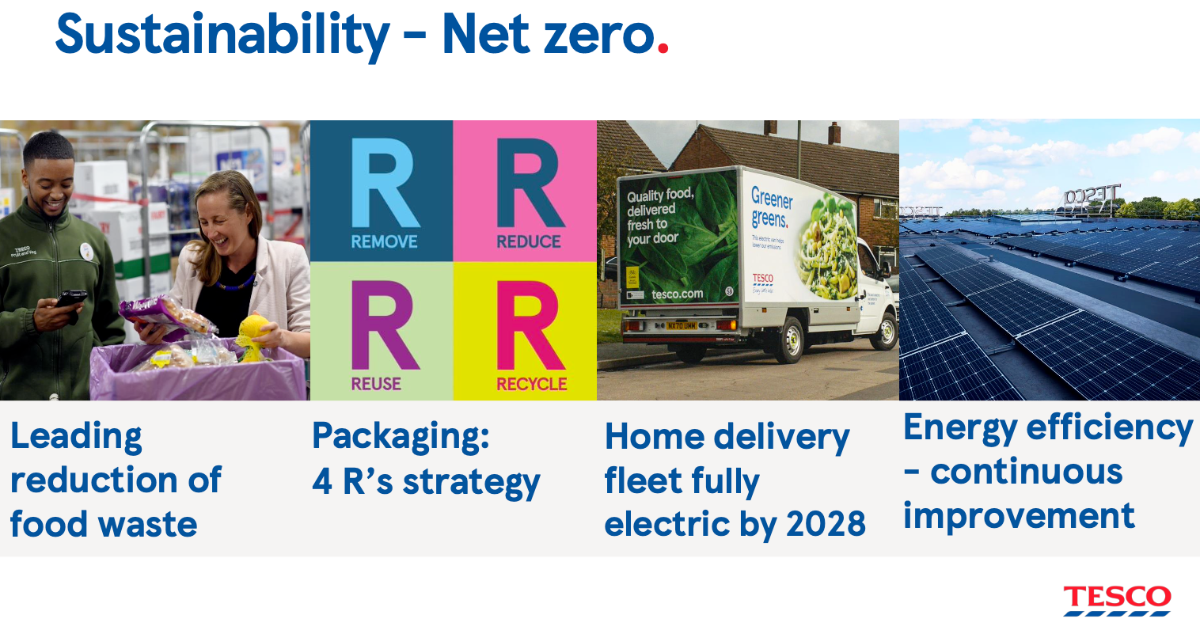
Sustainability is a huge focus and quite rightly to be fair, it's not just plastic, it's everything,. Sustainability is related to everything we produce, we import, we consume and it's about closing the loop to eliminate waste that both costs money, but also has an environmental impact.
Tesco mentioned that they are working with the government to electrify their fleet of delivery vehicles by 2028, a lot of work to do there with the infrastructure one would think, but a notable aim regardless.
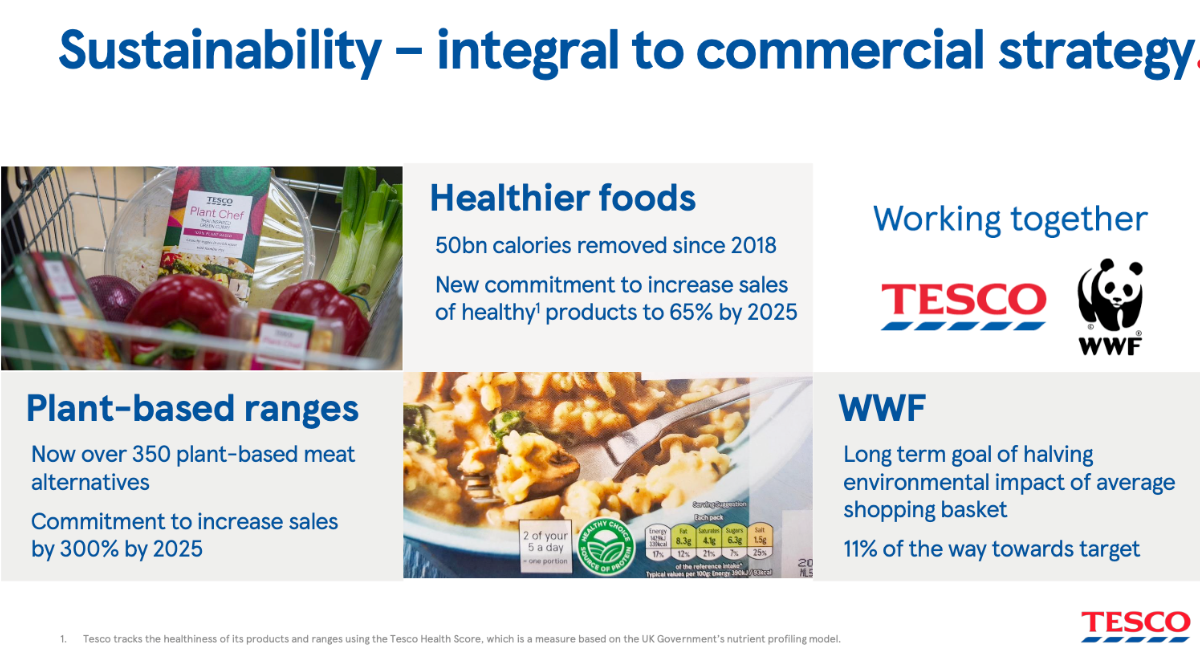
In addition - plant based ranges have been a success story for Tesco, with their Vegan work in Wicked Kitchen alongside their own mid tier label. Healthier foods is also a positive with fat coming out of the own label ranges via calorie content and healthy products rising to 65% of sales by 2025.
Of course, legislation incoming will prevent ends being dedicated to impulse products and other lines that are considered unhealthy.
Equally, clothing has a fair old footprint from a sustainability viewpoint. Travel, water, materials alongside other products that travel around the world for consumption. Work within the WWF will help this demonstrably, already, sustainable clothing has been noted in store.
Sustainability is key and for Tesco, with their scale, they have a great opportunity to drive this forward.
Lots to consider.
Sales good but fuelled with COVID, price strategy working but blessed with COVID driving people to larger stores where queues are perhaps not as plentiful.
Their safety score with customers was very strong so the work around COVID19 worked, signage was strong and clearly, customers felt secure in store.
Their outlook looks to be focusing on pushing same day service and the instant delivery almost, like Uber Eats, or similar.
Their store network is talked about as a positive, rather than negative and there is little talk of being over spaced, as UFC for online can now take the excess space and improve both the metrics for online and the service levels of the offering.
Ken also wants Tesco to protect market share, so expect more aggression versus their larger rivals, not just Aldi and Lidl. In addition, behaving like a challenger brand means they may well be more aggressive in terms of range and promotions also.
Especially with the clubcard data usage, allowing them to target customers in a meaningful and relevant way. All very interesting...
From the Grocery Insight newsletter archive, first sent to subscribers on 14 April 2021. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.